UAE VAT penalties changed on 14 April 2026. A new Cabinet decision cut several fines and replaced the old late payment charge with a flat 14% per year.
This guide follows the Federal Tax Authority (FTA) penalty table, so you can see what you really owe. It covers every VAT fine, worked examples, and the steps to reduce or challenge a penalty.
Quick answer: UAE VAT penalties include AED 10,000 for late registration, AED 1,000 for a late return (AED 2,000 if repeated within 24 months), and 14% per year, charged monthly, on VAT paid late. These rates apply under Cabinet Decision No. 129 of 2025 from 14 April 2026.
UAE VAT Penalties at a Glance (2026 Table)
This table follows the FTA’s consolidated penalty decision. Table 1 (tax procedures) and Table 3 (VAT) were amended by Cabinet Decision No. 129 of 2025, effective 14 April 2026.
Violation
Penalty (AED)
Late VAT registration
10,000
Late deregistration
1,000, plus 1,000 each month, up to 10,000
Late VAT return
1,000; 2,000 if repeated within 24 months
Late payment of VAT
14% per year, charged monthly, for each month or part of a month
Incorrect VAT return
500 (not charged if corrected in time)
Voluntary disclosure of an error
1% of the tax difference per month
Not disclosing before an audit notice
15% of the tax difference, plus 1% per month
Not keeping records
10,000; 20,000 if repeated within 24 months
Records not given in Arabic when requested
5,000
Not notifying changes to your tax record
1,000; 5,000 if repeated within 24 months
Tax invoice or credit note not issued in time
2,500 per detected case
Prices not shown including tax
5,000
Not facilitating the tax auditor
20,000
Designated Zone conditions breached
Higher of 50,000 or 50% of the tax on the goods
The sections below explain each group in plain words.
What Changed in the UAE VAT Penalties on 14 April 2026?
Cabinet Decision 129 of 2025 in plain words
The Cabinet issued Decision No. 129 of 2025 on 9 October 2025. The Federal Tax Authority announced that it took effect on 14 April 2026.
It amends the penalty tables of Cabinet Decision No. 40 of 2017, the decision that sets fines under the tax procedures, VAT and Excise laws. The new late payment and disclosure rates now follow the same monthly method used for Corporate Tax, which matters if you also handle corporate tax filing.
Registration and deregistration penalties did not change.
Old rates vs new rates
Violation
Before (up to 13 April 2026)
After (from 14 April 2026), AED
Records not given in Arabic
20,000
5,000
Not notifying changes to tax record
5,000, then 10,000
1,000, then 5,000
Legal representative not notifying appointment
10,000
1,000
Late payment
2% after the due date, then 4% a month, capped at 300%
14% per year, charged monthly
Incorrect return
1,000, then 2,000
500
Voluntary disclosure
5% to 40%, by delay
1% per month
No disclosure before audit
50% plus 4% monthly
15% plus 1% monthly
The first three rows match the cuts the FTA itself listed when the decision came into force. The new column matches the current FTA table.
Do old penalties change?
The consolidated decision gives the effective date, 14 April 2026, but it does not say how balances from before that date are treated. If you have an older penalty, ask the FTA or a registered tax agent before you pay.
UAE VAT Penalties for Registration and Deregistration
Late VAT registration penalty
The penalty is AED 10,000 if a taxable person does not apply on time. Some older pages still say AED 20,000, but that figure is not in the current FTA table.
You may also owe VAT from the date your business should have registered. For the registration limit and the deadline, read our guide on VAT registration requirements in the UAE.
Late deregistration penalty
If you must deregister and you are late, the penalty is AED 1,000. Then another AED 1,000 applies on the same date each month, and the total stops at AED 10,000.
Late VAT Return Penalty in the UAE
First and repeat offence
A registrant who files late pays AED 1,000. If it happens again within 24 months, the penalty is AED 2,000.
A legal representative who files late faces the same amounts. They pay from their own funds.
Nil returns
Every VAT registrant must file a return for each tax period, even with no sales. A late nil return draws the same AED 1,000 late filing penalty, so file every period, even when the figures are zero.
Return due dates
VAT returns, and the VAT payable, are due within 28 days after the end of the tax period, as the FTA page on filing VAT returns and making payments explains.
For a tax period that ended on 30 September 2026, the return and payment are due by 28 October 2026.
Put the date in your calendar two weeks early. A missed date can cause two penalties: one for the late return and one for late payment.
Late VAT Payment Penalty: The 14% Rule
Late payment is usually the most expensive VAT penalty.
What the official table says
The penalty is 14% per year, charged monthly, on the unpaid tax. It applies for each month or part of a month. It starts the day after the due date and repeats on the same date each month.
For a voluntary disclosure, the due date is 20 business days from submission. For a tax assessment, it is 20 business days from receipt.
Why “part of a month” matters
Fourteen percent a year is about 1.1667% a month. Even if you pay 10 days late, the table counts a full month. Pay as early as you can.
Formula: unpaid tax × 14% ÷ 12 × number of months or part months.
Example: You owe AED 100,000 and pay 10 days late. The charge is 100,000 × 14% ÷ 12 = AED 1,166.67, the same as a full month.
The penalty row itself shows no cap. The old rules had a 300% cap.
There is also a general legal limit. Article 24(4) of the Tax Procedures Law (Federal Decree-Law No. 28 of 2022) says an administrative penalty cannot exceed two times the tax it relates to. In 2025, the Federal Supreme Court read this limit as applying to each penalty on its own, not to the total of all penalties in one assessment.
So the 14% monthly charge keeps running, but a single penalty cannot pass twice the tax.
Worked examples
Unpaid VAT of AED 100,000:
Months unpaid
Penalty (AED)
1
1,166.67
3
3,500
6
7,000
12
14,000
Illustration using the official rate. Your actual charge is set by the FTA.
The old rule vs the new rule
Until 13 April 2026, late payment cost 2% on the day after the due date, then 4% a month, up to 300%. Under the new rule, a long delay can still cost a lot, because the charge continues. But the first-day jump is gone, and the charge is monthly, not daily.
Incorrect VAT Return and Voluntary Disclosure Penalties
The AED 500 incorrect return penalty
Submitting an incorrect return carries AED 500.
You avoid it if:
You fix the return by the filing deadline, or
You file a voluntary disclosure that shows no difference in the tax due.
Voluntary disclosure: 1% per month
Found an error after filing? Tell the FTA. A voluntary disclosure carries 1% of the tax difference for each month or part of a month. The count runs from the day after the return’s due date until you submit the disclosure.
Waiting for an audit: 15% plus 1% per month
If you do not disclose before the FTA notifies you of an audit, the penalty is a fixed 15% of the tax difference, plus 1% per month.
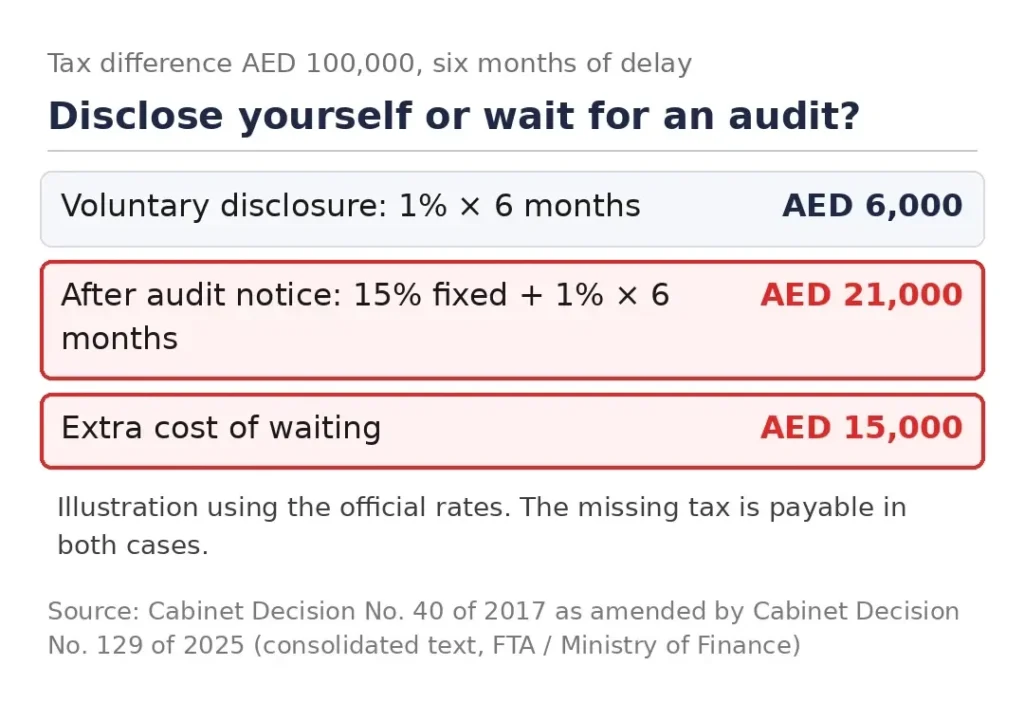
Disclose now or wait? An example
Assume a tax difference of AED 100,000 and six full months of delay.
Route
Calculation
Total (AED)
Disclose yourself
1% × 6 months × 100,000
6,000
Wait for an audit notice
(15% × 100,000) + (1% × 6 × 100,000)
21,000
Illustration using the official rates. It assumes six chargeable months, for example a return due in April and a disclosure filed in late October. Exact dates change the result. Waiting costs AED 15,000 more in this example.
Any penalty is on top of the tax. The decision states that a penalty does not cancel the duty to pay the due tax.
Record Keeping, Arabic Records and Changes to Your Tax Record
Violation
Penalty (AED)
Not keeping required records
10,000 per violation; 20,000 if repeated within 24 months
Not giving records in Arabic when the FTA asks
5,000
Not telling the FTA about changes to your tax record
1,000; 5,000 if repeated within 24 months
The record keeping penalty is AED 10,000 for a first offence, not AED 1,000 as some older pages show.
Keep tax invoices, credit notes, import documents and return workings. Have the key papers ready in Arabic when the FTA asks.
Changes to report include a new address, a new activity, or a change of legal form. Update your profile on EmaraTax quickly.
Tax Invoice, Credit Note and Price Display Penalties
Violation
Penalty (AED)
Tax invoice or alternative document not issued in time
2,500 per detected case
Tax credit note or alternative document not issued in time
2,500 per detected case
Electronic invoice conditions not met
2,500 per detected case
Prices not shown including tax
5,000
Margin scheme use not notified
2,500
Example: The FTA finds 10 missing invoices. The penalty is 10 × 2,500 = AED 25,000.
Older figures of AED 5,000 per invoice or AED 15,000 for price display do not match the current table.
Designated Zone Penalties
If you break the conditions for keeping goods in a Designated Zone, or moving them between zones, the penalty is the higher of AED 50,000 or 50% of the tax on the goods. Compare both numbers; the larger one applies.
Penalties for Legal Representatives, Tax Agents and Auditor Obstruction
Person
Violation
Penalty (AED)
Legal representative
Not notifying the FTA of the appointment
1,000
Legal representative
Filing a return late
1,000; 2,000 if repeated
Person under audit, tax agent or legal representative
Not helping the tax auditor
20,000
The FTA table says these amounts are paid from the person’s own funds, not the company’s.
Import Tax Penalties
Not calculating the tax due on imported goods carries a penalty of 50% of the unpaid or undeclared tax.
Not calculating tax for another person, when you must, carries the same 14% per year monthly charge as late payment.
How UAE VAT Penalties Stack
Penalties do not replace each other. One mistake can trigger several.
Example 1: Late return and late payment
A business owes AED 12,000 in VAT. The return is due 28 April. It files and pays on 8 May.
Item
Calculation
AED
Late return (first offence)
Fixed
1,000
Late payment (one part month)
12,000 × 14% ÷ 12
140
Penalties
1,140
VAT itself
12,000
If the payment waits three months, the late payment charge becomes 12,000 × 14% ÷ 12 × 3 = AED 420, and penalties total AED 1,420.
Illustration. The FTA ledger sets the final figure.
Example 2: Wrong return, found by the FTA
Incorrect return: AED 500.
No disclosure before the audit notice: 15% plus 1% a month on the tax difference.
You also owe the missing tax.
Example 3: Sloppy paperwork
Five missing invoices: 5 × 2,500 = AED 12,500.
No records when asked: AED 10,000.
Older VAT Penalty Figures That Still Appear Online
Many figures still online come from earlier years. Here is how they compare with the current FTA table.
Item
Older figure still online
FTA table (2026)
Late registration
AED 20,000
AED 10,000
Price shown without tax
AED 15,000
AED 5,000
Missing tax invoice
AED 5,000
AED 2,500
Records not in Arabic
AED 20,000
AED 5,000
Not keeping records, first time
AED 1,000
AED 10,000
Late payment
2% then 4% a month, capped
14% per year, monthly
Late payment timing
“Daily”
Monthly, per month or part
When two figures disagree, trust the FTA decision.
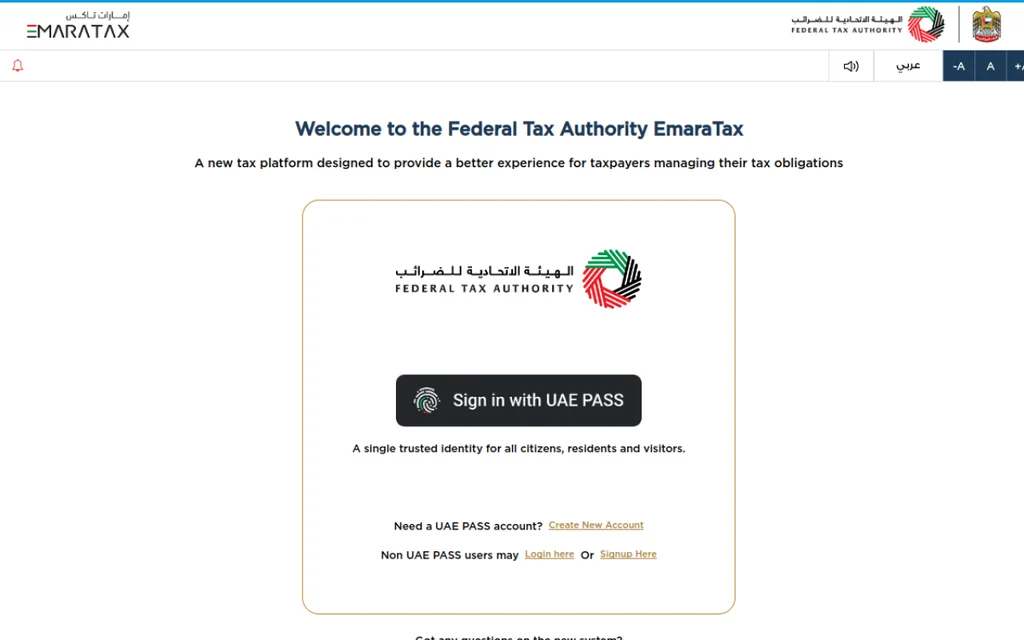
Screenshot: FTA EmaraTax sign-in page on the official tax.gov.ae website (captured October 2026).
Log in with UAE PASS.
Open your Taxable Person profile.
Check your notifications, payables and penalty notices.
Pay through the portal.
Keep the receipt.
Menu names on the dashboard can change, so follow the labels on your own screen. Watch for official FTA email and SMS alerts, and ignore payment links from unknown senders.
Can You Reduce or Waive a UAE VAT Penalty?
Yes, in some cases. The FTA has two separate routes. Do not mix them up.
Fix the violation, and give an undertaking not to repeat it
Instalment conditions
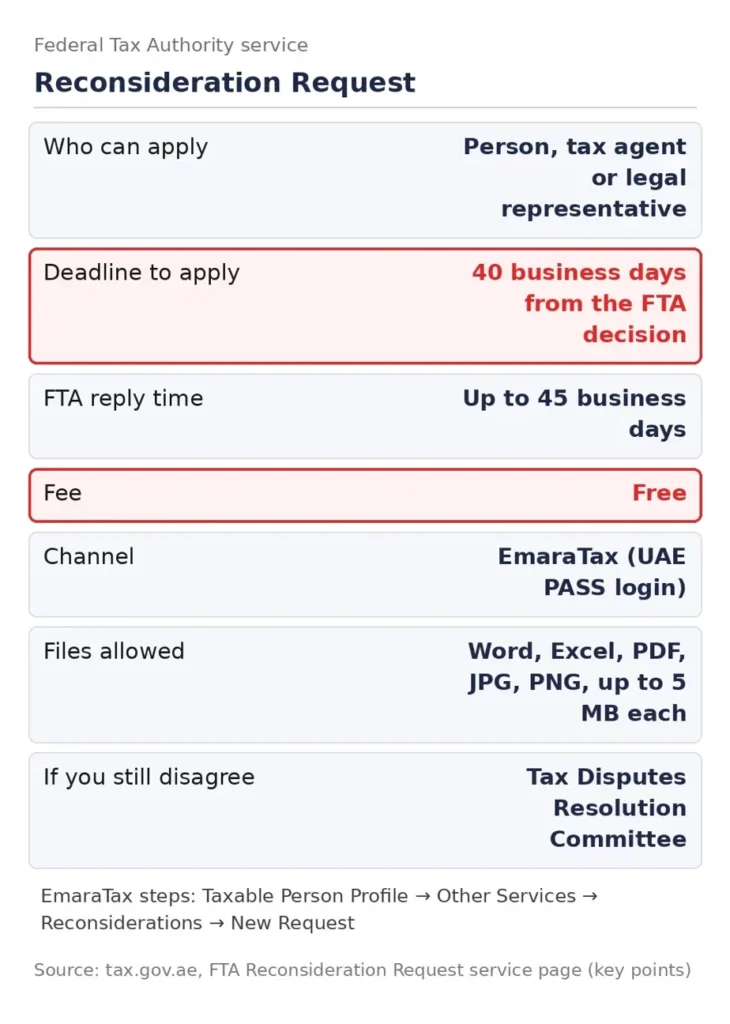
Only unpaid penalties count; you must not owe payable tax for the period; the penalties must not be disputed before the TDRC or a court (a reconsideration request is allowed)
Instalment minimum
AED 50,000 in total penalties, although the Committee may change it
Review time
Up to 110 business days
Fee
Free
Where
EmaraTax, with UAE PASS
Which route should you choose?
Your situation
Route
You think the FTA decision is wrong
Reconsideration request
The penalty is correct, but you want relief
Waiver request, if you meet the conditions
You want to pay a large penalty in parts
Instalment request, if you meet the conditions
You are unsure how a penalty or disclosure works
A registered tax agent
Keep proof of payment, the penalty notice and your correction records ready for any route.
Screenshot: Requests for Installment, Waiver and Refund of Administrative Penalties service on the official tax.gov.ae website (captured October 2026).
Tax Evasion vs Administrative Penalties
Administrative penalties are for mistakes and missed duties. Tax evasion is a crime under Article 25 of the Tax Procedures Law (Federal Decree-Law No. 28 of 2022).
It covers deliberate acts such as giving false data to the FTA or hiding and destroying records. The law sets imprisonment and a fine of not less than the evaded tax and up to three times that amount, or one of the two. This guide is general information, not legal advice.
How to Avoid UAE VAT Penalties
Use this checklist:
Set calendar reminders two weeks before each deadline.
File every period, including nil returns.
Pay on or before the due date, not just file.
Review figures before you submit. An incorrect return costs AED 500 unless fixed in time.
Correct errors early through a voluntary disclosure. It costs far less than waiting for an audit.
Issue tax invoices and credit notes on time. Check that prices include tax.
Keep records and be ready to give Arabic versions when asked.
Update your EmaraTax profile whenever your details change.
Run a short yearly VAT health check with your accountant.
If your business also pays Corporate Tax, check our guide to corporate tax registration requirements. Corporate Tax has its own penalty rows in the same Cabinet decision.
UAE VAT Penalties Updates: 2025 to 2026
Date
Update
9 Oct 2025
Cabinet Decision No. 129 of 2025 issued
Nov 2025
Consolidated version of Cabinet Decision No. 40 of 2017 published
14 Apr 2026
New penalty rates take effect
28 Oct 2026
Due date for returns for tax periods ending 30 September 2026
How We Verified This Guide
We built the penalty tables from the consolidated text of Cabinet Decision No. 40 of 2017, as amended by Cabinet Decision No. 129 of 2025. We checked the reconsideration and waiver details on the FTA’s service pages, and the penalty cap and tax evasion rules in Federal Decree-Law No. 28 of 2022.
This guide is not tax or legal advice. For a live case, speak to a registered tax agent. The decision does not say how penalties from before 14 April 2026 are treated, so confirm any older balance with the FTA.
Conclusion
UAE VAT penalties are lighter in many areas now, and late payment runs at a flat 14% per year, charged for every month or part of a month. A short delay still costs a full month, and the penalty row shows no cap of its own.
Keep four rules in mind:
Use the FTA table, not old blog numbers.
File and pay on time, even with nil returns.
Fix errors early. Disclosing yourself can save thousands compared with an audit.
If a penalty looks wrong, use reconsideration. If it is right but heavy, ask for a waiver or instalments.
Check your EmaraTax dashboard each month and keep clean records. Your trade licence has its own deadlines too, so read our guide to the trade licence fine in Dubai before renewal time.
FAQs About UAE VAT Penalties
What are the UAE VAT penalties in 2026?
They include AED 10,000 for late registration, AED 1,000 for a late return (AED 2,000 if repeated within 24 months), AED 500 for an incorrect return, and 14% per year, charged monthly, on VAT paid late. These apply from 14 April 2026.
What is the penalty for late VAT payment in the UAE?
It is 14% per year on the unpaid tax, charged monthly for each month or part of a month. On AED 100,000, that is about AED 1,166.67 per month.
What is the penalty for late VAT return filing?
AED 1,000 for the first late return. AED 2,000 if it is repeated within 24 months.
What is the penalty for late VAT registration in the UAE?
AED 10,000 under the current FTA table. See our guide on VAT registration requirements for the deadline.
How is the 14% late payment penalty calculated?
Divide 14% by 12 to get about 1.1667% per month. Multiply by the unpaid tax and by each month or part of a month. The penalty row shows no cap, but under Article 24(4) of the Tax Procedures Law a single penalty cannot exceed twice the tax.
What is the penalty for an incorrect VAT return?
AED 500. You avoid it by correcting the return by the filing deadline, or by filing a voluntary disclosure that shows no difference in due tax.
How much does a voluntary disclosure cost under the new rules?
1% of the tax difference per month, from the day after the return’s due date until you submit the disclosure.
What is the penalty for not issuing a tax invoice?
AED 2,500 per detected case under the current table. The same amount applies to credit notes and to electronic invoice condition breaches.
Do I need to file a nil VAT return?
Yes. Every registrant files a return for each tax period, even with no sales, and a late nil return draws the AED 1,000 late filing penalty.
Can UAE VAT penalties be waived?
Yes, in some cases. The FTA offers waiver and instalment requests under Cabinet Decision No. 105 of 2021, and reconsideration requests for decisions you think are wrong. Both are free on EmaraTax.
How do I request VAT penalty reconsideration on EmaraTax?
Log in with UAE PASS, open your Taxable Person profile, go to Other Services, then Reconsiderations, then New Request. Raise it within 40 business days of the FTA decision.
Can I pay UAE VAT penalties in instalments?
Yes, if the total unpaid penalties are at least AED 50,000 (the Committee may amend this) and you meet the FTA conditions. Review can take up to 110 business days.
Anees is a UAE-based content creator, writer, and SEO professional with over 12 years of experience. Since 2014, he has published research-backed guides on UAE visas, labour laws, jobs, traffic fines, and government services, all verified against official sources. He is certified in SEO by HubSpot Academy and Digital Marketing by Google Digital Garage.
12+ Years ExperienceHubSpot Academy — SEOGoogle Digital Garage
Disclaimer: This information is for general guidance only, based on publicly available UAE laws and regulations. It does not constitute legal advice. Always verify with official UAE government sources or a qualified legal professional.





Your email will not be published. Comments are reviewed before appearing.