UAE Visa Overstay Fine 2026: AED 50/Day RulesMinimum Salary to Sponsor Your Family Visa in UAEUAE Labour Law: Notice Period ExplainedHow to Check Your UAE Visa Status OnlineUAE Golden Visa Eligibility Requirements UpdatedUAE Visa Overstay Fine 2026: AED 50/Day RulesMinimum Salary to Sponsor Your Family Visa in UAEUAE Labour Law: Notice Period ExplainedHow to Check Your UAE Visa Status OnlineUAE Golden Visa Eligibility Requirements Updated
Corporate Tax Filing UAE: Deadlines, Documents and How to File
The UAE Times
–
–
– min read
Last updated: – · Based on official UAE sources
Corporate tax filing UAE follows one core rule: every taxable person must submit their return through EmaraTax within 9 months of their tax period ending, and pay any tax due by the same deadline. This sits alongside the other businesses in UAE topics owners deal with regularly.
Filing is required even if no tax is actually payable, and free zone companies aren’t exempt just because they qualify for the 0% rate. This guide covers exactly when to file, what documents to prepare, how the EmaraTax process works, and what penalties apply if you’re late.
Corporate Tax Filing UAE at a Glance
Question
Short Answer
Where do I file?
FTA’s EmaraTax platform
How often?
Once for each tax period
When is it due?
Generally within 9 months after the tax period ends
Who files?
Every taxable person, including free zone entities
Standard rate
0% up to AED 375,000 taxable income, 9% above that
Zero tax payable?
A return may still be required
Records
Generally at least 7 years, longer may apply in specific cases such as outstanding refund claims
Small Business Relief
Available through tax periods ending on or before 31 December 2029
Corporate Tax Registration vs Corporate Tax Filing
These are genuinely separate obligations, worth spelling out clearly.
Corporate Tax Registration
Corporate Tax Filing
Gets you
A Tax Registration Number
Reports your actual tax position
Frequency
One time
Once for each tax period
Result
Registered with the FTA
Submitted return, tax settled
Does it replace the other?
No
No
Having a Corporate Tax Registration Number does not mean you’ve completed your annual corporate tax compliance. If you haven’t registered yet, our guide on UAE corporate tax registration requirements covers that earlier step.
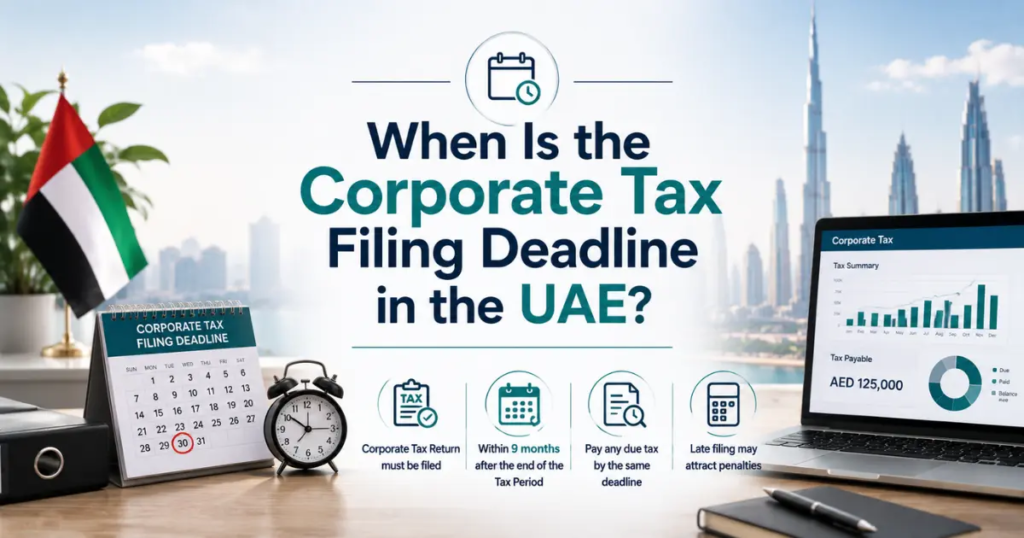
When Is the Corporate Tax Filing Deadline in the UAE?
9 months from the end of your tax period. For a business with a financial year ending 31 December, that means a filing deadline of 30 September the following year.
Filing Is Not the Same as Registration
Registering for corporate tax and getting your TRN is a one-time step. Filing is a separate, recurring obligation, once for every tax period, even after registration is long complete. Businesses sometimes assume registration alone means they’re compliant, it doesn’t.
Corporate Tax Filing Deadline Examples
Tax Period Ends
Filing Deadline
31 December
30 September (following year)
31 March
31 December (same year)
30 June
31 March (following year)
30 September
30 June (following year)
Is the 7-Month Deadline Still Relevant?
The 7-month window applied specifically to a late-registration-penalty waiver, not the standard filing deadline itself, and this waiver has largely expired for most businesses by 2026. Don’t confuse it with your actual 9-month filing deadline.
Does the Deadline Depend on My Registration Date?
No. The filing deadline is calculated from your tax period end date, not from when you registered, received your TRN, or renewed your trade licence.
Who Needs to File Corporate Tax in the UAE?
Every taxable person subject to UAE corporate tax must submit a corporate tax return for each relevant tax period, including UAE-incorporated companies, free zone entities, foreign companies with a UAE permanent establishment, and natural persons running a business with annual revenue over AED 1 million. Certain exempt persons that are required to register have an annual declaration obligation instead of a standard return.
Who Doesn’t Need to File a Standard Return?
Not everyone files the same document. Certain exempt persons, such as qualifying government entities and specific public benefit categories, submit an annual declaration instead of a standard tax return, a genuinely distinct filing obligation, not a full exemption from reporting to the FTA entirely.
Do You Still Need to File If You Owe No Tax?
Yes. A return is generally still required even where taxable income is below AED 375,000, where the business has a tax loss, or where a relief or election applies. Filing and payment are separate obligations, you can have zero tax payable and still need to submit the return itself.
Do Free Zone Companies Need to File Corporate Tax Returns?
Free zone companies are still subject to corporate tax compliance. A Qualifying Free Zone Person may benefit from a 0% rate on qualifying income, but it still has to register, maintain records, and file its corporate tax return, generally within the same 9-month deadline. Filing is also how the FTA confirms ongoing eligibility for that preferential treatment.
Check QFZP Status Before Making Your Election
A Free Zone Person can elect to be subject to the standard corporate tax rules instead of the QFZP regime. This decision has a major consequence: once made, the election applies to the relevant tax period and the following 4 tax periods. Confirm your QFZP eligibility and overall tax position carefully before making this election in your first return, not after.
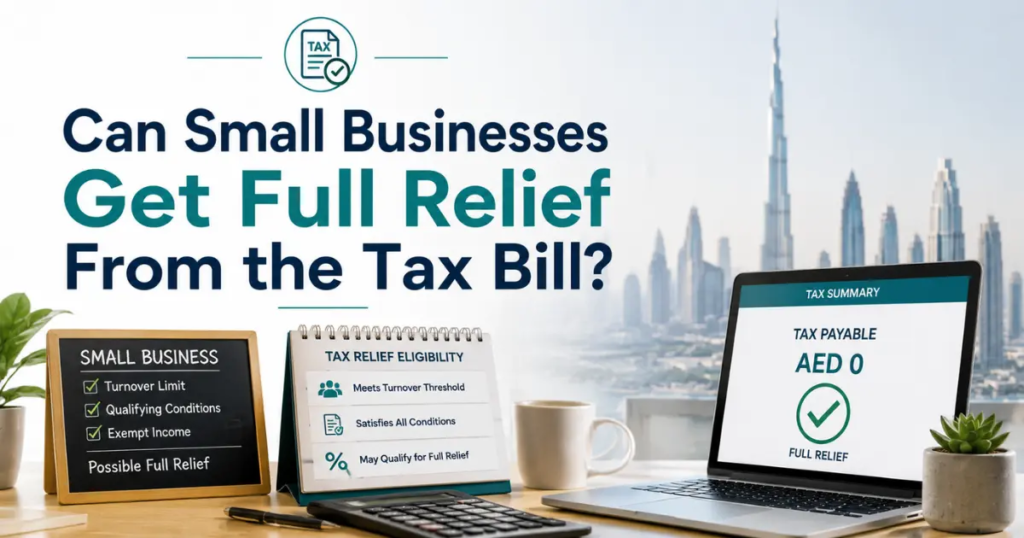
Can Small Businesses Get Full Relief From the Tax Bill?
Not from filing itself, but from the tax bill. Qualifying small businesses can claim Small Business Relief, treated as having zero taxable income entirely, provided:
Revenue, not profit, doesn’t exceed AED 3 million during the current tax period and all previous periods
The business elects the relief directly through its tax return
The business isn’t part of a multinational enterprise group with consolidated group revenue exceeding AED 3.15 billion
The business isn’t a Qualifying Free Zone Person, since QFZP status and Small Business Relief are mutually exclusive, you choose one path or the other, not both
Don’t confuse this AED 3 million revenue threshold with the AED 375,000 taxable income threshold that determines your standard tax rate, they’re two genuinely different thresholds measuring two different things.
This extends the relief window from the previous 31 December 2026 end date to tax periods ending on or before 31 December 2029
The AED 3 million threshold itself hasn’t changed, only the window during which the relief remains available
Some older articles and even some FTA-adjacent pages still reference the earlier 2026 cut-off, since they predate this August 2026 amendment, so treat any source citing 2026 as outdated
Businesses claiming this relief can’t also apply certain other reliefs, such as tax loss carryforwards, in the same period.
What Documents Do You Need to File Corporate Tax?
Finalised financial statements, prepared under IFRS or IFRS for SMEs
Trial balances and detailed workings supporting your tax computation
This is genuinely a point of confusion worth getting right. Audited financial statements are required for:
A Qualifying Free Zone Person, regardless of whether its revenue is below AED 50 million
A taxable person whose revenue exceeds AED 50 million in the relevant tax period
A tax group, which prepares audited special-purpose aggregated financial statements
Don’t treat the AED 50 million threshold as applying to QFZPs, it doesn’t. A small QFZP with modest revenue still needs an audit specifically because of its QFZP status, not because of how much it earns.
How to File Corporate Tax in the UAE, Step by Step
Log in to EmaraTax using your Tax Registration Number
Confirm your pre-populated tax period is correct before proceeding
Complete the return form, which uses different sections and schedules depending on your specific circumstances
Complete the Transfer Pricing Disclosure Form if your business meets the relevant threshold
Review your calculated taxable income and any elections or reliefs claimed
Submit the return
Pay any tax due via GIBAN or another FTA approved method
What If I’m Eligible for Small Business Relief?
You still need to file, using a simplified Corporate Tax Return rather than being exempt from filing entirely.
When Should You Pay Corporate Tax?
Corporate tax due must be settled by the same deadline as your tax return. Don’t wait until the final day, since the FTA considers the applicable payment rules when determining whether tax was settled on time. If paying by bank transfer, allow enough processing time for the funds to actually reach the FTA rather than assuming an initiated transfer counts as paid.
What Happens If You File or Pay Late?
AED 500 per month, or part of a month, for the first 12 months
AED 1,000 per month from the 13th month onward, continuing until you file
Late payment carries 14% annual interest on top of these penalties
These are separate from the AED 10,000 penalty for missing the registration deadline entirely
What Happens If Your Return Contains an Error?
An incorrect tax return can result in an administrative penalty of AED 500. This penalty does not apply where you correct the return before the deadline for submitting that return.
Other Filing-Related Penalties
Inadequate record-keeping: AED 10,000 for a first violation, rising to AED 20,000 for a repeat violation within 24 months
How Much Does It Cost to File Corporate Tax?
The FTA doesn’t charge a government fee simply to file your return, the cost is your actual tax liability (if any), plus whatever you spend on preparing the return yourself or engaging a Registered Tax Agent or accountant.
Can You Correct a Mistake After Filing?
Yes, through a voluntary disclosure submitted to the FTA. Under the reformed penalty framework effective 14 April 2026, this is genuinely worth doing promptly.
Voluntary disclosure before the FTA issues an audit notice: 1% monthly penalty on the identified tax difference
Disclosure after an audit notice has already been issued: a 15% fixed penalty plus 1% monthly charges
The exact penalty depends on when the error is disclosed and whether the FTA has already notified you of a tax audit, so treat these as the two general scenarios rather than a rigid formula for every situation.
This is the same broader 2026 penalty reform that also changed VAT and Excise Tax penalties, correcting your own error early is consistently the cheaper path across all three taxes. If you’re also managing VAT alongside corporate tax, our guide on VAT registration UAE requirements covers that separate obligation many businesses handle in parallel.
Conclusion
Two things matter most about corporate tax filing UAE. First, taxable persons subject to corporate tax must generally file their returns, including free zone persons, even where no corporate tax is payable. Second, the 7-month figure some guides mention refers to a largely expired registration-penalty waiver, not your actual filing deadline, and Small Business Relief now runs through 2029, not 2026 as some older sources still claim.
Confirm your specific tax period and any applicable reliefs directly through EmaraTax or a Registered Tax Agent before your deadline approaches.
Frequently Asked Questions
When Is the Corporate Tax Filing Deadline in the UAE?
The Corporate Tax filing deadline in the UAE is generally within 9 months from the end of the company’s Tax Period. For example, if a company’s Tax Period ends on 31 December, its Corporate Tax Return is due by 30 September of the following year.
Do I Need to File Corporate Tax If I Owe No Tax?
Yes. A business generally still needs to file its Corporate Tax Return in the UAE even if it has no tax payable. This can apply when taxable income is below AED 375,000, the business has a tax loss, or an applicable relief results in zero taxable income.
Do Free Zone Companies Need to File Corporate Tax Returns?
Yes. Free Zone companies generally need to file a Corporate Tax Return, including Qualifying Free Zone Persons that benefit from the 0% Corporate Tax rate on qualifying income. The 0% rate does not remove the company’s Corporate Tax registration, record keeping and filing obligations.
What Is the Penalty for Late Corporate Tax Filing in the UAE?
The penalty for late Corporate Tax filing is AED 500 per month or part of a month for the first 12 months, increasing to AED 1,000 per month from the 13th month onward until the return is submitted. Late payment of Corporate Tax can also result in separate penalties and interest on the unpaid amount.
What Documents Do I Need to File Corporate Tax in the UAE?
Businesses should have their finalised financial statements, trial balances, supporting schedules and account reconciliations ready for the Corporate Tax return. Audited Financial Statements may also be required, including for Qualifying Free Zone Persons regardless of revenue and for Taxable Persons whose revenue exceeds AED 50 million, subject to the applicable rules.
Who Needs to File Corporate Tax in the UAE?
Taxable Persons subject to UAE Corporate Tax generally need to file a Corporate Tax Return for each relevant Tax Period. This can include UAE incorporated companies, Free Zone entities, foreign companies with a UAE Permanent Establishment, and natural persons conducting a business or business activity in the UAE where their annual turnover exceeds AED 1 million.
How Much Does It Cost to File Corporate Tax in the UAE?
The Federal Tax Authority does not charge a separate government fee simply for submitting a Corporate Tax Return. The total cost can include any Corporate Tax payable and professional fees if the business uses an accountant, tax consultant or Registered Tax Agent to prepare and submit the return.
Can Small Businesses Get Relief From Corporate Tax in the UAE?
Yes. Eligible businesses can claim Small Business Relief if their revenue does not exceed AED 3 million in the relevant Tax Period and they meet the other conditions. The relief has been extended to Tax Periods ending on or before 31 December 2029. The AED 3 million threshold is based on revenue, not taxable profit.
Who Cannot Claim Small Business Relief in the UAE?
A Qualifying Free Zone Person cannot claim Small Business Relief because the two regimes cannot be used together for the same Tax Period. The relief is also unavailable to businesses that are part of a multinational enterprise group with consolidated group revenue exceeding AED 3.15 billion, along with other excluded categories under the Corporate Tax rules.
What Happens If a Business Elects Not to Be Treated as a QFZP?
A Free Zone Person that elects to be subject to the standard Corporate Tax rules instead of the Qualifying Free Zone Person regime cannot simply reverse that election in the next Tax Period. The election generally applies to the relevant Tax Period and the following four Tax Periods. Businesses should therefore confirm their QFZP eligibility and tax position carefully before making the election.
Updates Section
Last verified: August 2026. Reflects current FTA published deadlines, penalty structure, the Corporate Tax Returns Guide CTGTXR1, and the Small Business Relief extension announced 7 August 2026.
Anees is a UAE-based content creator, writer, and SEO professional with over 12 years of experience. Since 2014, he has published research-backed guides on UAE visas, labour laws, jobs, traffic fines, and government services, all verified against official sources. He is certified in SEO by HubSpot Academy and Digital Marketing by Google Digital Garage.
12+ Years ExperienceHubSpot Academy — SEOGoogle Digital Garage
Disclaimer: This information is for general guidance only, based on publicly available UAE laws and regulations. It does not constitute legal advice. Always verify with official UAE government sources or a qualified legal professional.
Your email will not be published. Comments are reviewed before appearing.