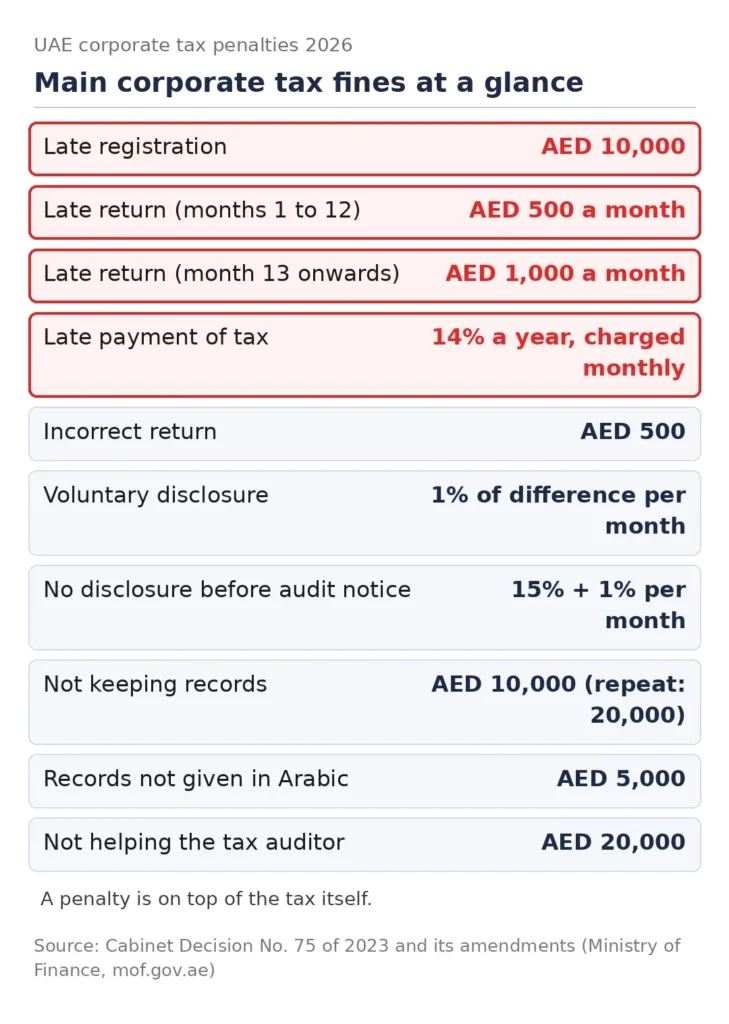
UAE corporate tax penalties range from AED 500 for an incorrect return to AED 20,000 for blocking a tax audit. The biggest costs usually come from late registration, late filing and late payment.
This guide follows the official penalty decision, Cabinet Decision No. 75 of 2023. It lists every fine, shows worked examples, and explains how to reduce a penalty.
Quick answer: The main UAE corporate tax penalties are AED 10,000 for late registration, AED 500 per month for a late return (AED 1,000 per month after 12 months), and 14% per year, charged monthly, on tax paid late. The 2026 VAT update did not change this corporate tax table.
UAE Corporate Tax Penalties at a Glance
Cabinet Decision No. 75 of 2023 sets these fines. The Cabinet issued it on 10 July 2023, and it took effect on 1 August 2023. Cabinet Decision No. 10 of 2024 later amended the late registration row, from 1 March 2024.
#
Violation
Penalty (AED)
1
Not keeping records
10,000; 20,000 if repeated within 24 months
2
Records not given in Arabic when requested
5,000
3
Late deregistration
1,000, plus 1,000 each month, up to 10,000
4
Not notifying changes to your tax record
1,000; 5,000 if repeated within 24 months
5
Legal representative not notifying appointment on time
1,000
6
Legal representative filing a late return
500 per month for 12 months, then 1,000 per month
7
Registered person filing a late return
500 per month for 12 months, then 1,000 per month
8
Late payment of tax
14% per year, charged monthly, for each month or part of a month
9
Incorrect return
500, unless corrected before the due date
10
Voluntary disclosure of an error
1% of the tax difference per month
11
Not disclosing before an audit notice
15% of the tax difference, plus 1% per month
12
Not facilitating the tax auditor
20,000
13
Late declaration by an exempt person who must submit one
500 per month, then 1,000 per month
14
Late registration application
10,000
Rows 5 and 6 are payable from the legal representative’s own funds. Row 12 is payable by the person, legal representative or tax agent responsible, as applicable.
The sections below explain each group in simple words.
Which Law Sets UAE Corporate Tax Penalties?
Three texts work together:
Federal Decree-Law No. 47 of 2022 is the Corporate Tax Law. It sets who pays tax and what they must file.
Federal Decree-Law No. 28 of 2022 is the Tax Procedures Law. It sets the general rules for registration, returns, audits and penalties.
Cabinet Decision No. 75 of 2023 is the penalty table. It lists the exact amount for each corporate tax violation.
The penalty table has its own rule. For corporate tax violations, it replaces the older VAT penalty table. This is why UAE corporate tax penalties differ from VAT penalties.
Some figures still found online do not match the official table:
What you may see online
What the official table says
Incorrect return AED 1,000, or AED 2,000 if repeated
AED 500
Late payment 2% plus 4% per month
14% per year, charged monthly
Voluntary disclosure 5% to 40%
1% of the tax difference per month
Small Business Relief ends in 2026
Extended to tax periods ending by 31 December 2029
The first three come from the old VAT table. They never applied to corporate tax.
Late Registration Penalty: AED 10,000
The UAE corporate tax penalty for late registration is AED 10,000.
You pay it when you miss your registration deadline. Free zone companies, mainland companies and many individuals with a business licence must register.
Is the late registration waiver still available?
The FTA waiver has strict conditions.
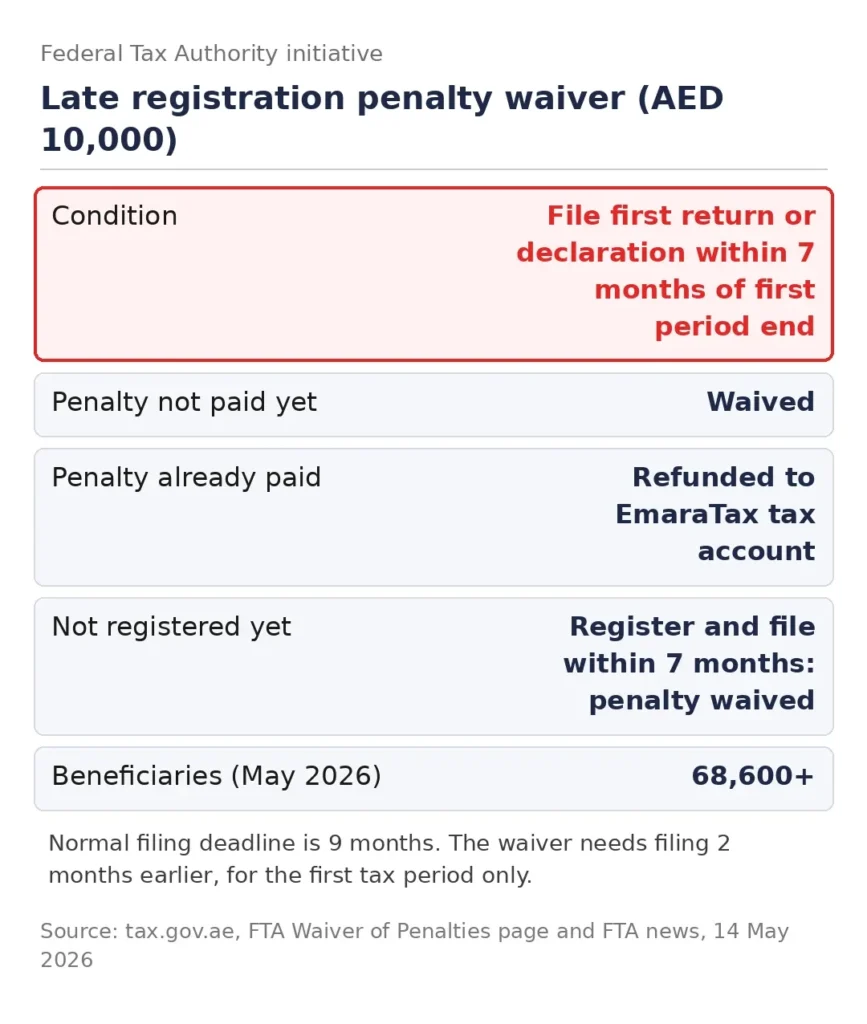
Who qualifies: taxable persons, and exempt persons who must register, that file their first return or annual declaration within 7 months of the end of their first tax period. The normal deadline is 9 months.
The 31 July 2025 date: this was the cut-off for taxpayers whose first tax period ran from 1 January to 31 December 2024. Other taxpayers have their own date, based on their first tax period.
What happens if you qualify: the FTA waives the AED 10,000. If you already paid, it refunds the amount to your tax account on EmaraTax.
Scale: more than 68,600 taxpayers had benefited by May 2026, and the FTA expects the number to pass 91,000.
Do not assume the date fits your company. Check your first tax period and the current FTA waiver terms. If you missed your date, register and file now. Then ask the FTA or a licensed UAE tax advisor whether you still qualify.
The late filing penalty is AED 500 per month for the first 12 months. It rises to AED 1,000 per month from the 13th month.
This applies to registered persons and to legal representatives who file for others. Count the chargeable months from the day after your deadline.
The filing deadline
Under the Corporate Tax Law, you must file your return and pay the tax within 9 months after the end of your tax period.
Tax period ends
Deadline
31 December 2025
30 September 2026
31 March 2026
31 December 2026
30 June 2026
31 March 2027
Deadline and penalty start
Return due date: 9 months after the period end. File and pay by this date.
Late filing: AED 500 starts to build for each month you stay late.
Late payment: 14% per year starts to build on the unpaid tax. It is a separate charge.
Late filing and late payment are two different penalties. You can pay on time and still file late, or the reverse. Our guide on how to file corporate tax in the UAE walks through the return on EmaraTax.
A company with a 31 December 2025 year end that missed 30 September 2026 is already late. Each new month adds AED 500.
Exempt persons who must register also have a duty
Some exempt entities must still register. If you are one of them, you file an annual declaration instead of a return. Not every exempt entity has this duty, so check your category.
The late declaration penalty is the same: AED 500 per month, then AED 1,000 per month.
Late Payment Penalty: 14% Per Year
The UAE corporate tax penalty for late payment is 14% per year on the unpaid tax. The FTA charges it monthly. A part of a month counts as a full month.
The simple formula
Unpaid tax × 14% ÷ 12 × number of months or part months
Worked example
Assume a company owes AED 100,000 in corporate tax. It pays and files after 3 chargeable months or part months. The unpaid balance stays the same.
Item
Calculation
Amount (AED)
Late payment
100,000 × 14% ÷ 12 × 3
3,500
Late filing
500 × 3
1,500
Total penalties
5,000
The company pays AED 5,000 on top of its tax. A part month counts as a full month, so a delay of 2 months and 5 days gives 3 chargeable months. This example is indicative. The FTA assessment decides the real amount.
Other payment rules
If you pay after a voluntary disclosure or an FTA assessment, the due date is 20 business days later.
If a month has no matching date (for example 31 February), the last day of that month counts, under Article 3 of the decision.
Use the same method for any late payment amount. Only the tax figure changes.
Incorrect Return and Voluntary Disclosure Penalties
Incorrect return: AED 500
You pay AED 500 if your return has a mistake. You pay nothing if you fix it before the due date.
Voluntary disclosure: 1% per month
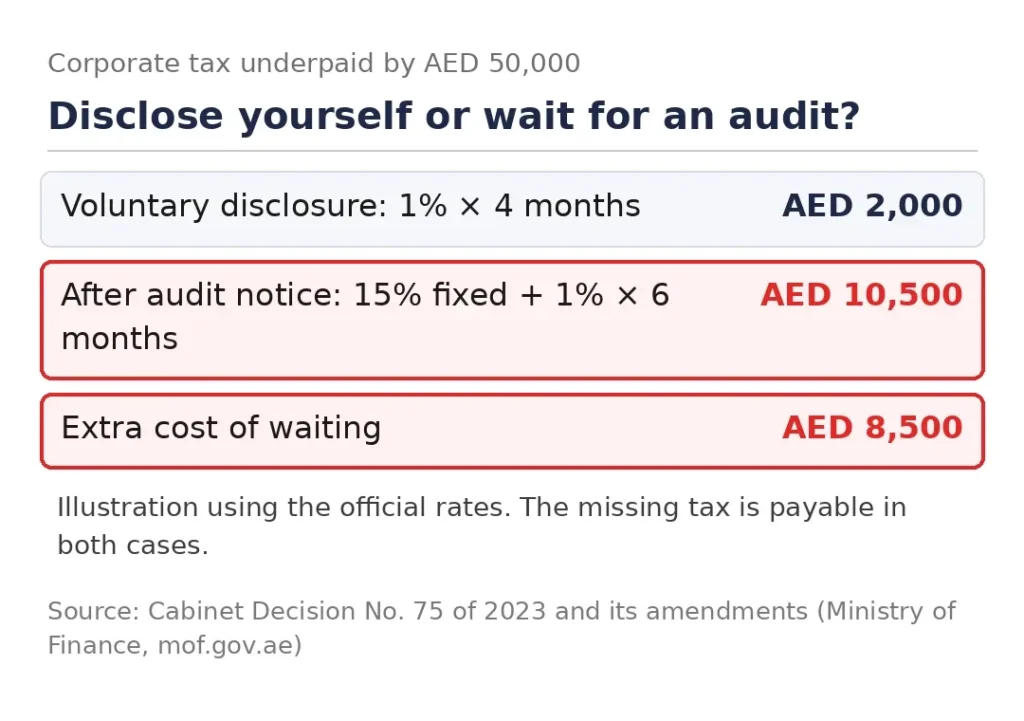
A voluntary disclosure is not a relief route. It is the way to correct an error in a return, an assessment or a refund application. It carries its own penalty: 1% of the tax difference for each month or part of a month until you disclose. The count usually starts from the original due date.
Not disclosing before an audit notice: 15% plus 1%
If the FTA sends an audit notice before you disclose, the penalty jumps. You pay 15% of the tax difference once, plus 1% for each month.
Compare the three
Situation
Penalty
You fix the error before the due date
None
You disclose after filing, before any audit notice
Gets an audit notice first, with 6 chargeable months: 15% is AED 7,500, plus 1% × 6 months is AED 3,000. The total is AED 10,500.
These are indicative examples. The exact start and end of the monthly count depend on the case.
Early disclosure saves AED 8,500 in this example.
Record Keeping and Arabic Records Penalties
Not keeping records: AED 10,000
You pay AED 10,000 if you fail to keep the records the law requires. The fine doubles to AED 20,000 if you repeat it within 24 months.
Keep your financial statements, invoices, contracts and bank records. The Corporate Tax Law says you must keep them for 7 years after the end of the tax period.
Records not given in Arabic: AED 5,000
The FTA can ask for records in Arabic. You pay AED 5,000 if you fail to provide them.
Tip: ask your accountant to prepare an Arabic copy of key documents before an audit starts.
Other Administrative Penalties
Not notifying changes: AED 1,000
You must tell the FTA when your tax record changes. This includes your name, address, legal form or activity. The penalty is AED 1,000. It rises to AED 5,000 if you repeat it within 24 months.
Late deregistration
If you close your business, you must apply to deregister. The penalty is AED 1,000, plus AED 1,000 per month. The total stops at AED 10,000.
Legal representative penalties
A legal representative acts for a taxpayer, for example for a non resident. The penalties are:
AED 1,000 for not notifying the FTA of the appointment on time.
AED 500 per month for a late return, then AED 1,000 per month after 12 months.
The representative pays both from personal funds.
Blocking the tax audit: AED 20,000
You pay AED 20,000 if you do not help the tax auditor. The person, legal representative or tax agent responsible pays it, as applicable. Name a contact person early, so the auditor gets answers fast.
UAE Corporate Tax Penalties vs VAT Penalties
Both taxes now use a similar method. Some amounts still differ.
Violation
Corporate tax
VAT (from 14 April 2026)
Late registration
AED 10,000
AED 10,000
Late return
AED 500 per month, then AED 1,000
AED 1,000; AED 2,000 if repeated
Late payment
14% per year, charged monthly
14% per year, charged monthly
Incorrect return
AED 500
AED 500
Voluntary disclosure
1% per month
1% per month
No disclosure before audit
15% plus 1% per month
15% plus 1% per month
Records
AED 10,000; AED 20,000 if repeated
AED 10,000; AED 20,000 if repeated
Arabic records
AED 5,000
AED 5,000
Tax invoice not issued
Not applicable
AED 2,500 per case
The big difference is the late return fine. Corporate tax adds a new charge every month. VAT charges a fixed amount.
Penalties for Free Zone, Small Business and Exempt Persons
Free zone companies
Free zone companies must register and file. A free zone licence does not remove the duty.
Qualifying Free Zone Persons can pay 0% on qualifying income. If a company fails the conditions, it can lose that rate. This is a tax result, not a penalty from the table above. Check the FTA guide for your case.
Small Business Relief
Small Business Relief lets eligible small businesses be treated as having no taxable income. The revenue limit is AED 3 million, under Ministerial Decision No. 73 of 2023.
Eligibility has more conditions. The FTA looks at revenue across the relevant tax periods, not only the current one. Qualifying Free Zone Persons and some multinational groups cannot claim the relief. Meeting AED 3 million in one period does not prove eligibility.
On 7 August 2026, the Ministry of Finance extended the relief to tax periods ending on or before 31 December 2029.
Relief does not cancel your filing duty. You still register and file. A late filing penalty can still apply.
Exempt persons
Exempt persons file an annual declaration. Missing it triggers the same monthly penalty as a late return.
Can You Get a Corporate Tax Penalty Reduced or Waived?
Sometimes. The FTA offers three routes to challenge a penalty or ask for relief. They work the same way for VAT and corporate tax.
Challenge a penalty or ask for relief
Your situation
Route
You think the FTA decision is wrong
Reconsideration request
You have a valid reason and want the penalty waived
Waiver request
You cannot pay a large penalty at once
Instalment request
Reconsideration basics
You file it against an FTA decision, usually within 40 business days of the notice.
The FTA states it can take up to 45 business days to reply, and it may extend this.
Add your facts, legal grounds and proof.
Waiver and instalment requests fall under Cabinet Decision No. 105 of 2021. Instalments need at least AED 50,000 in unpaid penalties, and the FTA can take up to 110 business days to decide.
Screenshot: Requests for Installment, Waiver and Refund of Administrative Penalties service on the official tax.gov.ae website (captured October 2026).
If you find a mistake yourself, file a voluntary disclosure. It does not remove a penalty. It limits the damage, as the table above shows.
Screenshot: Reconsideration Request service on the official tax.gov.ae website (captured October 2026).
Is There a Penalty Cap? Are There Criminal Offences?
The cap
Article 24(4) of the Tax Procedures Law says an administrative penalty cannot exceed two times the tax it relates to. In 2025, the Federal Supreme Court read this limit as applying to each penalty on its own, not to the total.
Do not rely on the cap for planning. A monthly penalty still runs until you file or pay.
Criminal offences
This guide covers administrative penalties. Tax evasion is a crime under Article 25 of the Tax Procedures Law. It covers deliberate acts such as giving false data to the FTA or hiding records, and it carries imprisonment and a fine from one to three times the evaded tax, or one of the two.
How to Avoid UAE Corporate Tax Penalties
Use this simple checklist:
Register before your deadline.
Write your return deadline in your calendar: 9 months after your year end.
Pay the tax on the same day you file.
Keep records for 7 years.
Save an Arabic copy of key documents.
Update the FTA when your details change.
Fix errors before the due date.
Use voluntary disclosure as soon as you find a mistake.
Reply fast to any FTA message on EmaraTax.
What to do by situation
You missed…
Do this now
Registration
Register today and ask the FTA or a tax advisor about the waiver
A return
File immediately, and pay the tax
A payment
Pay now, because the 14% runs each month
An error in a filed return
File a voluntary disclosure before any audit notice (it limits the penalty, it does not waive it)
Common Mistakes That Cause Penalties
Thinking a free zone licence means no filing. It does not.
Mixing up the financial year and the tax period. Check the period on EmaraTax.
Using old VAT numbers. The corporate tax table is different.
Waiting for a reminder. The FTA does not need to remind you for a penalty to start.
Assuming Small Business Relief ends the filing duty. It does not.
Conclusion
UAE corporate tax penalties are simple once you see the table. Most costs come from three things: late registration at AED 10,000, a monthly late filing fine, and 14% per year on late tax.
The 2026 penalty update did not change this table. The late registration waiver has strict conditions, so check yours. The best protection is a calendar reminder, early payment and fast correction of any error.
If you have already missed a deadline, act now. File, pay and then ask about relief. Each extra month adds cost.
FAQs About UAE Corporate Tax Penalties
What are the UAE corporate tax penalties?
UAE corporate tax penalties are administrative fines for breaking corporate tax rules. They include AED 10,000 for late registration, AED 500 per month for a late return, and 14% per year on late tax. Cabinet Decision No. 75 of 2023 sets them.
What is the penalty for late corporate tax filing in the UAE?
The penalty is AED 500 per month for the first 12 months. From the 13th month it is AED 1,000 per month.
What is the penalty for late corporate tax registration?
It is AED 10,000. An FTA waiver exists for eligible taxpayers who file their first return within 7 months of the period end. See the waiver section above for the conditions.
How is the corporate tax late payment penalty calculated?
Use unpaid tax × 14% ÷ 12 × months. A part month counts as a full month. On AED 100,000 paid 3 months late, the penalty is AED 3,500.
Can UAE corporate tax penalties be waived?
Sometimes. You can file a reconsideration, waiver or instalment request on EmaraTax. Reconsideration usually has a 40 business day limit. Approval depends on your case.
Is the late registration waiver still open?
It depends. The 31 July 2025 date applied to most taxpayers with a first tax period from 1 January to 31 December 2024, not to everyone. Check your first tax period and the current FTA terms.
What is the penalty for an incorrect corporate tax return?
It is AED 500. You pay nothing if you correct the error before the due date.
What is the penalty for not keeping corporate tax records?
It is AED 10,000, or AED 20,000 if you repeat it within 24 months. Not giving records in Arabic costs AED 5,000.
What is the corporate tax filing deadline?
It is 9 months after the end of your tax period. A 31 December 2025 year end means 30 September 2026.
Did UAE corporate tax penalties change in 2026?
No. The 2026 update changed VAT and Excise penalties. It did not amend the corporate tax table.
Is there a provisional tax penalty in the UAE?
No. UAE corporate tax has no provisional or advance tax payments. You pay the full tax once a year, with the return, so the penalties above are the ones you can face.
Do free zone companies pay corporate tax penalties?
Yes. Free zone companies must register and file. They face the same penalties for late action.
Who pays the penalty, the company or the owner?
The company pays most penalties. A legal representative pays the appointment and late return penalties from personal funds. The audit penalty falls on the person, legal representative or tax agent responsible.
What is the difference between corporate tax and VAT penalties?
Both use 14% for late payment and AED 500 for an incorrect return. The late return fine differs. Corporate tax charges every month. VAT charges a fixed amount.
Does Small Business Relief remove the filing duty?
No. Eligible businesses must still register and file. A late filing penalty can still apply. Eligibility has more conditions than the AED 3 million limit.
Anees is a UAE-based content creator, writer, and SEO professional with over 12 years of experience. Since 2014, he has published research-backed guides on UAE visas, labour laws, jobs, traffic fines, and government services, all verified against official sources. He is certified in SEO by HubSpot Academy and Digital Marketing by Google Digital Garage.
12+ Years ExperienceHubSpot Academy — SEOGoogle Digital Garage
Disclaimer: This information is for general guidance only, based on publicly available UAE laws and regulations. It does not constitute legal advice. Always verify with official UAE government sources or a qualified legal professional.






Your email will not be published. Comments are reviewed before appearing.