Newborn health insurance in the UAE must be arranged within 30 days of birth in Dubai, and cover can be backdated toward the date of birth within limits. Getting the timing right matters, because the cover window and the backdating limit are not the same thing.
The commonly cited AED 500 figure comes from Dubai’s health insurance law. A separate, earlier decision, maternity coverage timing, also catches many parents off guard before the baby arrives. This guide covers both, checked against Dubai’s law and ISAHD’s own policy directive.
Is Newborn Health Insurance in the UAE is Mandatory?
In Dubai, health insurance is mandatory for residents under Law No. 11 of 2013, and newborns are covered by specific newborn provisions in ISAHD’s policy directive. Other emirates have their own rules: in Abu Dhabi, for example, parents are expected to register a newborn for health insurance within 30 days of birth. Parents elsewhere should confirm the rules in their emirate.
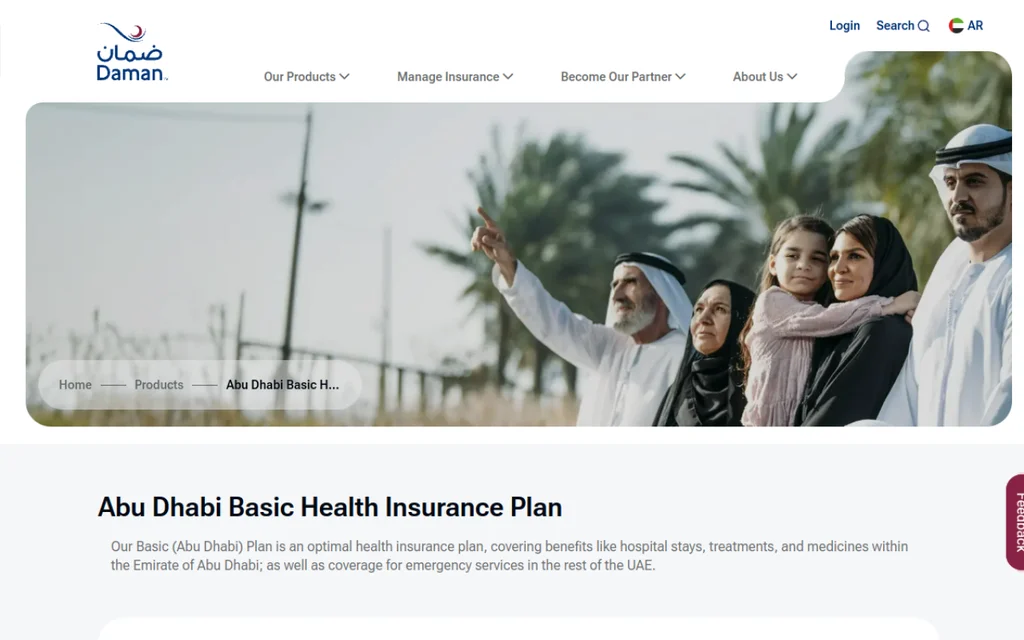
Screenshot: Daman Abu Dhabi Basic Health Insurance Plan page on the official damaninsurance.ae website (captured October 2026).
The 30-Day Rule in Plain Terms
A newborn is covered under the mother’s policy for up to 30 days from birth, or up to the mother’s annual limit, whichever comes first. Parents should arrange the baby’s own enrollment within this period and confirm with the insurer how the effective date will be handled, since backdating for newborn additions is capped at a maximum of 7 days under ISAHD’s own policy directive. The same directive also bars insurers from applying any waiting period or pre-existing condition exclusion to a newborn.
This means registering promptly, ideally within the first week, matters more than the full 30-day window suggests, if you want cover to run all the way back to the date of birth without a gap.
Some hospitals also require proof of active insurance before discharge, particularly where a newborn needs NICU or neonatal support, making early enrollment a practical necessity, not just a compliance one.
What Is the Fine for Not Insuring a Newborn?
This comes from Dubai’s Law No. 11 of 2013 Concerning Health Insurance.
The law provides for fines ranging from AED 500 to AED 150,000 for violations, with the specific penalty set under the applicable resolution and rules, not a single fixed figure written into the law itself. For how Dubai’s monthly fines work, see our guide on the health insurance fine in the UAE
The exact penalty applicable to a particular case should be confirmed with the relevant authority rather than assumed from a general figure
Missing the deadline also creates a real coverage gap: once the mother’s 30-day cover ends, the newborn is uninsured until their own policy starts
The Two Clocks: Insurance Deadline vs Visa Deadline
The insurance deadline and the visa deadline are two separate clocks.
Task
Deadline from Birth
Authority
Add newborn to health insurance
30 days
DHA / ISAHD
Obtain residence visa and Emirates ID
120 days
GDRFA / ICP
Complete the insurance step first, since the insurance card is one of the documents required for the visa application. Missing the 120-day visa deadline adds a fine of AED 100 a day. Once the visa is done, you can track the baby’s card with an Emirates ID status check. The exact newborn insurance process can differ by emirate, so parents outside Dubai should confirm the applicable requirements with their local health authority or insurer.
How to Register a Newborn for Health Insurance: Step by Step
Confirm the 30-day clock and your policy type, employer group vs individual or family
Obtain the birth certificate through DHA or the relevant Dubai channel
Gather supporting documents: birth certificate, both parents’ Emirates IDs and passports, existing policy details
Notify HR or contact your insurer or broker directly, stating clearly this is a newborn addition
Pay the premium and confirm exactly how the effective date will be handled, remembering backdating is capped at 7 days
Receive the member card, and verify the child’s active status in the ISAHD system
Who Is Responsible for Adding the Newborn?
The legal duty sits with the sponsoring parent, not the hospital or the insurer. How you act on it depends on your policy type.
Aspect
Employer (Group) Policy
Individual or Family Policy
Who you contact
Company HR or benefits team
Your insurer or broker directly
Who pays the added premium
Depends on company policy
The sponsor pays directly
Employers are not legally required to extend cover to dependents. If the group plan doesn’t cover family members, the sponsor must buy separate cover for the child. Once you’re insured, checking your health insurance status in the UAE confirms the newborn’s policy is active before you rely on it.
Documents Required to Add a Newborn
Newborn’s birth certificate, the core document, registration cannot proceed without it
Both parents’ Emirates IDs and passports
Newborn’s passport, if already issued
Existing policy details or member card
Completed insurer addition form
Vaccination card, required by some insurers specifically
How Much Does It Cost to Add a Newborn?
There’s no single joining fee. Adding a newborn usually adds the child’s own premium, pro-rated to the remaining policy year. For wider price ranges, see our guide to health insurance costs in the UAE.
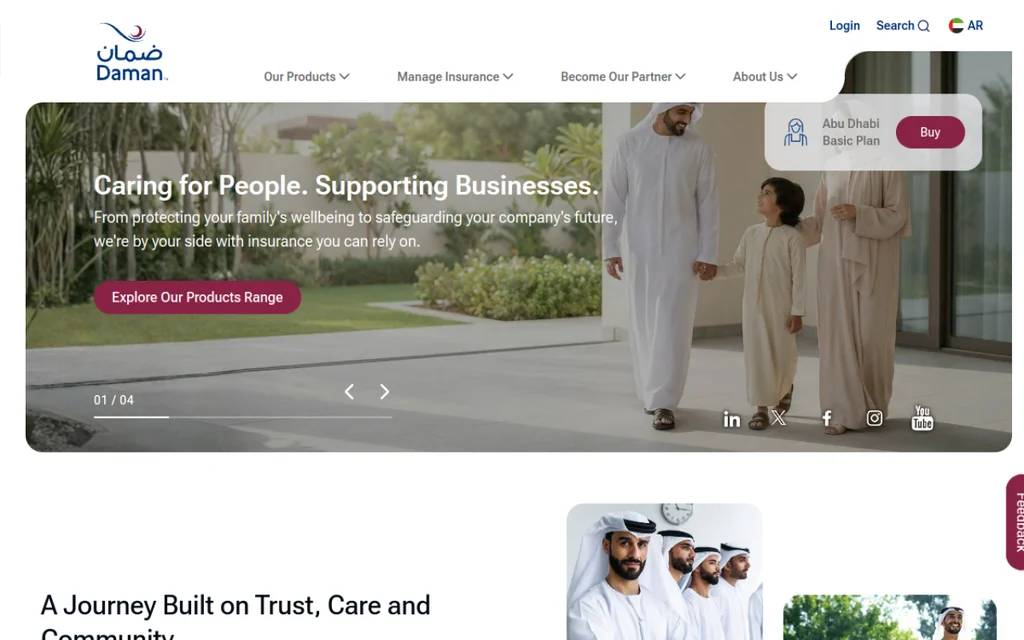
Screenshot: Daman homepage on the official damaninsurance.ae website (captured October 2026).
Example (official published rate)
Annual Premium
Abu Dhabi Basic Plan (Daman), child aged 0-17, individually insured family
AED 1,753.5 plus VAT
Abu Dhabi Basic Plan (Daman), child aged 0-17, additional family member
AED 1,522.5 plus VAT
Dubai plans
Set by each DHA-approved insurer; ask for a quote for the child
The Abu Dhabi figures are from Daman’s Basic Plan rate sheet effective 20 February 2026. Private plans with wider networks cost more, so confirm the child’s premium with your insurer.
Payment Flexibility
Some platforms now offer 0% interest installment payment options, splitting the premium into monthly payments rather than one lump sum.
Don’t Confuse This With the Maternity Waiting Period
This is a separate, earlier decision that many parents miss.
Maternity cover for the mother can carry a waiting period, and the length varies by insurer and plan, so check it before relying on the policy for a pregnancy
A policy purchased after pregnancy begins may also come with specific exclusions or limitations for that pregnancy
This is distinct from the newborn’s own 30-day post-birth addition rule, maternity coverage and newborn coverage are separate concepts
Families planning a pregnancy should check their plan’s exact waiting period well ahead of time, rather than assuming a specific figure applies
What Happens If You Miss the 30-Day Deadline?
The newborn becomes uninsured once the mother’s 30-day temporary cover ends
Care during any gap may need to be paid out of pocket
The sponsor is in breach of the mandatory insurance law
Visa and Emirates ID processing for the child stalls, since the insurance card is a required document
Late enrollment can mean extra paperwork with the insurer, and any days not covered by the 7-day backdating limit stay uninsured
Updates Section
Last updated: October 2026. Reflects Dubai’s Law No. 11 of 2013, ISAHD’s Policy Directive 11/2020 on maternity coverage and newborn additions, and Daman’s Abu Dhabi Basic Plan rates effective 20 February 2026.
Conclusion
The 30-day window is real, but backdating is limited to 7 days, so registering in the first week is the safest way to keep your baby covered from birth. It is also a separate decision from the mother’s maternity cover, which needs checking well before the baby arrives.
Confirm your specific policy’s terms and current fees directly with your insurer, HR team, or the Dubai Health Authority before assuming a figure from any single guide applies to your situation.
Frequently Asked Questions
How long do I have to add my newborn to health insurance in the UAE?
30 days from the date of birth in Dubai. The newborn is covered under the mother’s policy during this window, up to the mother’s annual limit. Backdating the baby’s own policy is capped at 7 days, so register early.
Is the AED 500 fine for newborn insurance real?
Dubai’s Health Insurance Law provides for fines ranging from AED 500 to AED 150,000 for violations, with the specific fine determined under the applicable rules. The exact penalty for a particular case should be confirmed with the relevant authority rather than assumed from a general figure.
Is the newborn’s cover backdated to the date of birth?
Backdating is possible but capped at a maximum of 7 days under ISAHD’s policy directive. Registering within the first week of birth gives you the best chance of continuous cover from day one, registering later in the 30-day window can still leave a gap the 7-day cap won’t close.
What documents do I need to add a newborn to insurance?
The birth certificate is the core document, alongside both parents’ Emirates IDs and passports, the existing policy details, and sometimes a vaccination card, depending on the insurer.
Is the 30-day insurance deadline the same as the visa deadline?
No. Health insurance must be arranged within 30 days, while the residence visa, Emirates ID and passport must be done within 120 days of birth. After that, a fine of AED 100 a day applies. Complete the insurance step first.
How much does it cost to add a newborn to health insurance?
There’s no separate joining fee. You pay the child’s own premium, pro-rated to the remaining policy year. On Abu Dhabi’s Daman Basic Plan, for example, a child aged 0-17 costs AED 1,522.5 to AED 1,753.5 a year plus VAT. Private plans cost more.
Does maternity coverage automatically include newborn coverage?
No, these are related but separate. Maternity coverage applies to the mother’s pregnancy and delivery and can carry its own waiting period, which varies by insurer. The newborn still needs to be added as their own dependent within the applicable window after birth.
Can I switch insurers after adding my newborn?
Yes, but it’s best to wait until your policy’s renewal cycle. Switching mid-term can create overlap issues or complications with claims during the transition.
What if my baby has health complications?
Declare any known health issues when you apply. In Dubai, ISAHD’s policy directive does not allow insurers to apply a waiting period or pre-existing condition exclusion to a newborn, so the baby should still be covered. Ask your insurer for written confirmation if you are unsure.
Can I dispute a late enrollment fine if the visa process caused the delay?
You can generally submit a formal appeal to DHA or DoH with documentation showing the delay was caused by administrative or government processing rather than parental inaction. Outcomes are handled case by case and aren’t guaranteed, so timely enrollment remains the safer approach.
Anees is a UAE-based content creator, writer, and SEO professional with over 12 years of experience. Since 2014, he has published research-backed guides on UAE visas, labour laws, jobs, traffic fines, and government services, all verified against official sources. He is certified in SEO by HubSpot Academy and Digital Marketing by Google Digital Garage.
12+ Years ExperienceHubSpot Academy — SEOGoogle Digital Garage
Disclaimer: This information is for general guidance only, based on publicly available UAE laws and regulations. It does not constitute legal advice. Always verify with official UAE government sources or a qualified legal professional.

Your email will not be published. Comments are reviewed before appearing.