UAE Visa Overstay Fine 2026: AED 50/Day RulesMinimum Salary to Sponsor Your Family Visa in UAEUAE Labour Law: Notice Period ExplainedHow to Check Your UAE Visa Status OnlineUAE Golden Visa Eligibility Requirements UpdatedUAE Visa Overstay Fine 2026: AED 50/Day RulesMinimum Salary to Sponsor Your Family Visa in UAEUAE Labour Law: Notice Period ExplainedHow to Check Your UAE Visa Status OnlineUAE Golden Visa Eligibility Requirements Updated
Health Insurance Costs in the UAE: Prices by Age, Emirate and Plan
The UAE Times
–
–
– min read
Last updated: – · Based on official UAE sources
There is no single figure for health insurance costs in the UAE. UAE medical insurance prices vary based on your age, emirate, coverage level, insurer, and the type of plan you choose. This sits alongside the other health and insurance topics UAE residents deal with regularly, and it’s one where the real answer depends on five things: your age, your emirate, your plan tier, your network, and whether you’re covered individually, through an employer, or as a family.
Quick Answer
Federal Basic Scheme (Northern Emirates): AED 320 a year for eligible groups
Dubai Basic/EBP: rates vary by participating insurer
Abu Dhabi Basic (Daman): age and category based, exact figures below
Private individual plans: commonly hundreds to several thousand dirhams a year
Comprehensive or international plans: can exceed AED 10,000 to 20,000+
Treat every figure in this guide as an indicative benchmark, not a guaranteed quote. Confirm your exact premium with a licensed UAE insurer.
Ranges are indicative market benchmarks, not guaranteed quotes.
Health Insurance Cost by Age
Age is one of the strongest drivers of your premium. Older brackets carry statistically higher claims frequency and chronic condition risk, which insurers price into the premium through underwriting bands.
Real Abu Dhabi Example by Age
This is confirmed directly onDaman’s own site, current as of early 2026.
Category
Age 18-40
Age 41-59
Age 60+
Low-income employee/worker
AED 997.5
AED 1,522.5
AED 9,358
Small investor
AED 2,835
AED 3,465
AED 10,408
The jump at 60+ is dramatic, roughly 6 to 9 times the 18-40 rate on this specific plan. It’s a concrete illustration of age-based loading that most guides only describe in the abstract.
Health Insurance Cost by Emirate
Health Insurance Cost in Dubai
The health insurance price in Dubai, and medical insurance Dubai price more broadly, is regulated by the Dubai Health Authority (DHA). The Essential Benefits Plan (EBP) is the mandatory minimum for lower salary bands. Multiple DHA-approved insurers offer EBP at their own rates rather than one fixed government price, so figures vary by participating insurer. Basic vs Enhanced options mainly differ in network breadth and included benefits.
Health Insurance Cost in Abu Dhabi
Regulated by the Department of Health (DOH), administered largely through Daman. The Basic Plan follows the exact age-banded pricing shown above, with a separate, higher small-investor rate, and further categories, including family and dependent pricing, published directly on Daman’s site.
Health Insurance Cost in the Northern Emirates
Sharjah, Ajman, Ras Al Khaimah, Fujairah, and Umm Al Quwain fall under the same federal Basic Health Insurance Scheme for eligible employee and domestic worker groups, confirmed directly byMOHRE, at AED 320 a year. This is one unified scheme, not five separately priced ones.
UAE Basic Health Insurance Plans Compared
Federal Basic Scheme
Dubai EBP
Abu Dhabi Basic (Daman)
Cost
AED 320/year
Varies by insurer, from around AED 600-900+
AED 997.5-10,408/year by age/category
Regulator
MOHRE / Central Bank
DHA
DOH
Annual limit
Confirmed via MOHRE
Insurer-specific
AED 250,000
Pre-existing conditions
No waiting period
Standard waiting period applies
Standard waiting period applies
Region
Northern Emirates
Dubai
Abu Dhabi
No single UAE health insurance basic plan applies everywhere, this table puts all three side by side with real, sourced figures.
Health Insurance Cost by Plan Type
Every UAE health insurance plan sits on a ladder, and the tier you choose moves the price more than the insurer you pick within that tier.
Enhanced/Standard: wider hospital network, semi-private rooms, maternity and dental usually included
Comprehensive: highest limits, minimal co-pays, wide or international network
Premium international: worldwide access, top-tier private rooms, the highest premium band
The jump between tiers reflects real differences, network breadth, room type, co-payment level, and whether maternity and dental come included, not just a higher number for the same thing.
Health Insurance Cost for Individuals vs Families
Family cost does not simply multiply the individual rate. Insurers band pricing with real economies of scale.
Household
Annual Premium (Example, Enhanced Tier)
Individual
AED 2,500
Couple
AED 4,800
Family of 3
AED 6,500
Family of 4
AED 8,200
Family of 5+
AED 9,800
Reported family cost ranges vary meaningfully by source, from roughly AED 6,200 up to AED 33,500 a year for a family of four, depending on tier and emirate. Confirm the specific figure with your insurer rather than relying on one guide’s average.
How Much Does Health Insurance Cost Per Month in the UAE?
Most UAE policies are billed annually, but a monthly view helps with budgeting.
Tier
Annual
Roughly Per Month
Federal Basic Scheme
AED 320
AED 27
Basic/EBP
AED 600-900
AED 50-75
Enhanced
AED 2,500-3,500
AED 208-292
Comprehensive
AED 5,500-12,000+
AED 458-1,000+
What Factors Affect Health Insurance Cost in the UAE?
Age: younger applicants pay less, premiums rise with age
Emirate: Dubai and Abu Dhabi typically cost more than the Northern Emirates
Medical history and pre-existing conditions: insurers must underwrite regardless of history, but may apply a waiting period, commonly 6 months, and load the premium
Gender and maternity: premiums can differ, particularly during childbearing years
Family size: costs scale sub-linearly, not by simple multiplication
Coverage level: each added benefit raises the premium
Hospital network: local-only networks cost less than regional or worldwide access
Annual coverage limit: higher limits mean higher premiums
Co-payment: the percentage you pay per visit affects the base price
Deductible: a higher deductible, commonly AED 500-2,000, lowers the annual premium
Dental and optical benefits: these add cost when included as riders
Geographic coverage: UAE-only is cheaper than regional or worldwide
Individual vs group: group coverage costs less per person through risk pooling
What Does a Cheap Health Insurance Plan Actually Cover?
A Basic plan typically includes:
Inpatient care
Outpatient consultations
Diagnostics
Prescriptions
Emergency treatment
A mandated maternity minimum
What’s usually excluded: dental, optical, and access to a wider hospital network.
The cheapest premium isn’t automatically the best value. A low-cost plan with a high co-pay and a narrow network can cost more at the point of actual treatment than a slightly pricier plan with better terms.
Premium vs Out-of-Pocket Cost: What Will You Actually Pay?
What Is a Co-payment?
The percentage of a bill you pay yourself at the point of treatment, commonly 20% on Basic plans for services like diagnostics.
What Is Deductible?
A fixed amount you pay before your insurance starts contributing, separate from the co-payment. Common UAE deductibles range from AED 500 to AED 2,000 a year.
What Is an Annual Coverage Limit?
The maximum amount your insurer pays out in a policy year. Basic plans commonly cap around AED 150,000 to 250,000, comprehensive plans reach into the millions.
Why a Cheaper Policy Can Cost More When You Actually Use It
A low premium with a high co-pay and low annual limit shifts more cost onto you at claim time. Someone who visits doctors regularly or has ongoing treatment needs can end up paying more out of pocket on a cheap plan than they’d have paid in premium on a better-structured one.
Worked Example: A Lower Premium vs a Higher Premium Plan
This is illustrative, not a real quote. A Basic plan at AED 700 a year with a 20% co-pay on every visit can cost a frequent visitor more across a year of treatment than an Enhanced plan at AED 2,800 with a lower co-pay and better network access. The premium is only half the real cost picture.
Health Insurance Cost for Pre-Existing Conditions
The Federal Basic Scheme covers chronic and pre-existing conditions with no waiting period, confirmed directly on MOHRE’s own page, a genuinely uncommon benefit at this price point
Most private plans apply a standard waiting period, commonly 6 months, before covering a pre-existing condition
Some insurers load the premium based on declared conditions
Declaring everything honestly at application prevents claim rejection later
Health Insurance Cost for Maternity
Even a Basic plan is required to include a mandated maternity minimum, commonly AED 7,000 for a normal delivery or AED 10,000 for a medically necessary C-section, plus antenatal visits, subject to a co-payment
Fuller maternity cover, without that sub-limit, sits with Enhanced and Comprehensive tiers
Adding maternity or dental to a plan typically raises the base premium by around 15% to 30%
For the specific 30-day rule on adding a newborn once the baby arrives, our guide on newborn health insurance in the UAE covers that process in full.
Health Insurance Cost Without an Employer
Freelancers, investors, and self-sponsored residents buy health insurance directly from a licensed insurer, the same mandatory requirement applies regardless of employment status
Individual premiums for this route generally sit closer to the Enhanced or Comprehensive tiers, since you don’t benefit from an employer’s group rate
If you’re setting up your own small business and weighing employee cover at the same time, our guide on health insurance for small business owners in the UAE covers that side of the equation.
Employer vs Individual Health Insurance Cost
Group coverage is typically cheaper per person than an individual policy, since risk is pooled across a workforce
Industry benchmarks cite a 40% to 60% reduction, though this is a market indication, not a guaranteed saving for every group
Employees covered under an employer group plan receive coverage at no direct cost to themselves
UAE employers cannot deduct health insurance costs from employee salaries
How to Reduce Your Health Insurance Cost in the UAE
Choose a local-only network if you don’t travel or need international treatment
Accept a higher deductible in exchange for a lower annual premium
Skip dental or optical riders if you don’t currently need them
Buy coverage earlier, since premiums rise with age
Compare quotes annually rather than auto-renewing
Use employer group coverage where available
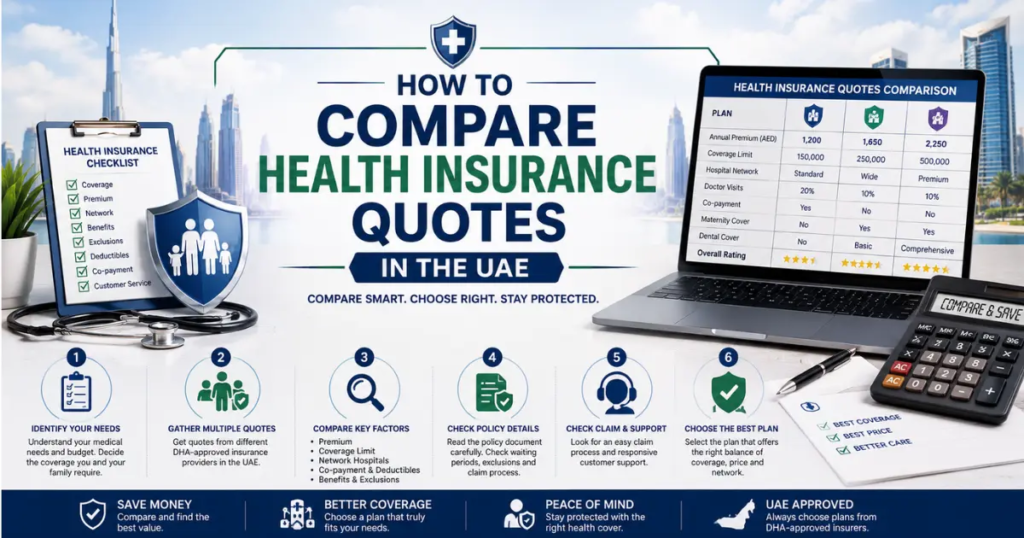
How to Compare Health Insurance Quotes in the UAE
Never compare two policies by premium alone. Check each of these before deciding:
Annual premium
Hospital network
Annual coverage limit
Inpatient, outpatient, and pharmacy benefits
Maternity and dental cover
Pre-existing condition terms and waiting period
Co-payment and deductible
Geographic coverage
Renewal terms and exclusions
Real Health Insurance Cost Examples
These are illustrative scenarios built from the ranges already confirmed in this guide, not literal quotes.
Young single resident, 25, Dubai, Basic plan: around AED 700 a year, narrow network, no dental
Married couple, early 30s, Abu Dhabi, Enhanced plan: around AED 4,800 a year combined
Family of four, Dubai, Enhanced plan with maternity and dental: around AED 8,200 a year
Resident aged 60+, Abu Dhabi, Basic (small investor category): around AED 10,408 a year
Self-sponsored investor, 35, Enhanced individual plan: around AED 2,800-3,500 a year
Low-income employee, Northern Emirates, federal scheme: AED 320 a year
What Is the Cheapest Health Insurance in the UAE?
The AED 320 federal scheme is the standout low-cost official option, but specifically for its eligible target groups, Northern Emirates employees and domestic workers under the income threshold. It isn’t the cheapest option for everyone in the UAE, eligibility genuinely matters here.
Is Cheap Health Insurance Worth It in the UAE?
A lower premium isn’t the same as a lower total cost. A cheap plan with a narrow network, high co-pay, and low annual limit can leave you paying significantly more out of pocket when you actually need care. Weigh the premium against the network, co-pay, and annual limit together, not the premium alone.
Health Insurance Cost vs Healthcare Cost Without Insurance
Health insurance in the UAE isn’t only a visa-compliance requirement, it transfers potentially large medical costs to the insurer under the policy’s terms. Hospitalisation, specialist consultations, diagnostics, surgery, and ongoing chronic treatment can run into tens of thousands of dirhams without cover. The premium you pay is genuinely small compared to the financial exposure it removes.
How to Get an Accurate Health Insurance Quote in the UAE
Information Insurers Normally Ask For
Age, emirate, visa type, Emirates ID or residency details, family members to be covered, medical history, pre-existing conditions, preferred hospitals, desired coverage level, maternity requirement, and geographic coverage.
Why Two People of the Same Age Can Get Different Quotes
Medical history, declared pre-existing conditions, chosen network, and coverage scope all shift the quote even at an identical age.
Why Online Estimates Aren’t Final Quotes
Online calculators and comparison tools give indicative, representative figures. Your actual premium is confirmed only after underwriting your specific details.
Conclusion
Two things matter most about health insurance costs in the UAE. First, your real price depends far more on your age, emirate, and chosen tier than any single average figure suggests, the Daman example alone shows a 6 to 9 times jump between the youngest and oldest age bands on the same plan.
Second, even the cheapest legal Basic plan includes a small mandated maternity benefit and, in the Northern Emirates federal scheme’s case, chronic condition cover with no waiting period, details worth knowing before assuming you need a pricier tier.
Request a personalised quote from a licensed UAE insurer for your specific age, emirate, and household before budgeting around any single number in this guide.
Frequently Asked Questions
How much does health insurance costs in the UAE?
Individual health insurance premiums can vary widely. Basic plans may start from around AED 320 to AED 900 per year, while enhanced and comprehensive policies can cost several thousand dirhams annually. The final premium depends on factors such as age, emirate, coverage level, insurer, network and medical history.
How much is health insurance per month in the UAE?
When annual premiums are divided into 12 months, basic coverage can work out to roughly AED 27 to AED 75 per month. Enhanced and comprehensive plans can cost considerably more. However, many UAE health insurance policies are priced and paid annually rather than monthly.
What is the cheapest health insurance in the UAE?
The Basic Health Insurance Scheme introduced for eligible private sector employees and domestic workers in Sharjah, Ajman, Fujairah, Ras Al Khaimah and Umm Al Quwain costs AED 320 per year. It is designed for specific eligible groups, so it is not a universal AED 320 policy for every UAE resident.
How much does health insurance cost in Dubai?
Health insurance prices in Dubai vary according to the insurer, age, coverage and provider network. Basic or Essential Benefits plans can start at relatively low annual premiums, while enhanced and comprehensive plans can cost substantially more. The exact price should be confirmed with a DHA approved insurer because premiums are not fixed across all providers.
How much does health insurance cost in Abu Dhabi?
Abu Dhabi health insurance costs vary by age and eligibility category. For example, Daman’s published Basic Plan premium schedule lists different annual premiums for low income employees, small investors and dependents, with premiums increasing substantially for older age groups. The published rates are also exclusive of VAT and other applicable taxes or fees.
How much does health insurance cost for a family of four in the UAE?
There is no fixed family health insurance price in the UAE. The total depends on the age of each family member, emirate, insurer, coverage level, network and benefits. A family with two young children can have a very different premium from a family that includes older parents.
Does health insurance cost more as you get older?
Yes. Age is one of the major factors affecting health insurance premiums in the UAE. Daman’s published Abu Dhabi Basic Plan rates, for example, show substantially higher premiums for people aged 60 and above than for younger adults.
How much does health insurance cost for people over 60 in the UAE?
The cost varies by insurer and plan. Under Daman’s published Abu Dhabi Basic Plan rates, the annual premium for people aged 60 and above can be significantly higher than the rate for younger adults. The exact amount depends on the person’s eligibility category and policy type.
Can I buy health insurance without an employer in the UAE?
Yes. People who are not covered through an employer can purchase health insurance themselves, depending on their residency and eligibility status. Self sponsored residents, investors and other individuals may need to arrange their own coverage rather than relying on an employer sponsored policy.
Does health insurance cover pre existing conditions?
It depends on the policy. The UAE’s Basic Health Insurance Scheme for eligible private sector employees and domestic workers covers chronic and pre existing conditions without a waiting period. Private health insurance policies can have different terms, including exclusions, waiting periods or premium adjustments, so the policy wording should always be checked.
What is the AED 320 health insurance scheme in the UAE?
The AED 320 Basic Health Insurance Scheme is a government introduced package for eligible private sector employees and domestic workers in Sharjah, Ajman, Fujairah, Ras Al Khaimah and Umm Al Quwain. The package costs AED 320 per year and has specific coverage limits, co payments and network conditions.
What is the difference between basic and comprehensive health insurance?
Basic health insurance is designed to provide essential medical coverage at a lower premium, usually with a more limited network and higher cost sharing for some services. Comprehensive health insurance generally costs more but can provide broader provider access, higher coverage limits and additional benefits depending on the policy.
Updates Section
Last verified: August 2026. Reflects MOHRE’s current Basic Health Insurance Scheme terms and Daman’s Abu Dhabi Basic Plan age-banded pricing, confirmed directly on Daman’s own site.
Anees is a UAE-based content creator, writer, and SEO professional with over 12 years of experience. Since 2014, he has published research-backed guides on UAE visas, labour laws, jobs, traffic fines, and government services, all verified against official sources. He is certified in SEO by HubSpot Academy and Digital Marketing by Google Digital Garage.
12+ Years ExperienceHubSpot Academy — SEOGoogle Digital Garage
Disclaimer: This information is for general guidance only, based on publicly available UAE laws and regulations. It does not constitute legal advice. Always verify with official UAE government sources or a qualified legal professional.
Your email will not be published. Comments are reviewed before appearing.