UAE Visa Overstay Fine 2026: AED 50/Day RulesMinimum Salary to Sponsor Your Family Visa in UAEUAE Labour Law: Notice Period ExplainedHow to Check Your UAE Visa Status OnlineUAE Golden Visa Eligibility Requirements UpdatedUAE Visa Overstay Fine 2026: AED 50/Day RulesMinimum Salary to Sponsor Your Family Visa in UAEUAE Labour Law: Notice Period ExplainedHow to Check Your UAE Visa Status OnlineUAE Golden Visa Eligibility Requirements Updated
Health Insurance Plan for Small Business Owners in the UAE: Complete Guide
The UAE Times
–
–
– min read
Last updated: – · Based on official UAE sources
Most small business owners don’t struggle to find health insurance. They struggle to know which rules apply to their company. A mainland company follows one route. A free zone business follows another. Choosing the wrong plan can delay visas, increase costs, or create compliance problems.
Choosing a health insurance plan for small business owners in the UAE starts with one question most guides skip: are you on the mainland or in a free zone? The rules, the authority you deal with, and the product options genuinely differ depending on the answer. This sits alongside the other health and insurance topics UAE residents and business owners deal with regularly.
Over 94% of UAE businesses are small or medium enterprises. This guide covers exactly what applies to yours, from mandatory compliance to real plan comparisons and costs.
Is Health Insurance Mandatory for Small Businesses in the UAE?
Yes, across all seven emirates. Private sector employers, including small business owners, must provide health insurance for every employee, though the exact rules and route depend on the emirate and business structure.
Mainland vs Free Zone: The Distinction Most Guides Miss
Mainland
Free Zone
Registers with
MOHRE
Free zone authority
Approved insurer type
DHA or DoH-approved insurer
Free zone-approved insurer
Workforce rules
Emiratisation quotas apply past 20 employees
Free zone’s own rules
Governing framework
Mainland labour law
Free zone regulations
Getting this distinction right at the start saves real time later.
Which Option Applies to You?
Mainland → follow the Dubai, Abu Dhabi, or Northern Emirates rules below
Free zone → check your free zone’s approved insurer list
1 to 10 employees → compare Micro-SME plans
Registered in the Northern Emirates → the federal Basic Scheme may be your cheapest option
What Is an Essential Benefits Plan (EBP)?
This is the actual term small business owners should search for or ask a broker about. An Essential Benefits Plan, sometimes called an SME Pre-Packaged Solution, is a simplified, budget-conscious, DHA-compliant medical insurance package built specifically for small and medium businesses.
Health Insurance Rules by Emirate for Small Businesses
Dubai
Regulated by the Dubai Health Authority (DHA). Employers select a DHA-approved insurer offering an Essential Benefits Plan or a custom small-group product.
Abu Dhabi
Regulated by the Department of Health (DoH), typically through Daman. Small business (Micro-SME) products like Value Choice are available for 1 to 10 employees.
Northern Emirates
Sharjah, Ajman, Fujairah, Ras Al Khaimah, and Umm Al Quwain are covered under the federal Basic Health Insurance Scheme, jointly run by MOHRE, ICP, and the Ministry of Health and Prevention.
The Federal Basic Health Insurance Scheme
For small businesses in the Northern Emirates, this is often the most cost-effective compliant route, and about as close to a genuinely low cost health insurance plan for small business owners in the UAE as it gets.
Detail
Figure
Cost
AED 320/year per employee
Inpatient co-payment
20%, up to AED 500/visit, AED 1,000/year cap
Outpatient co-payment
25%, up to AED 100/visit
Medication co-payment
30%, up to AED 1,500/year
Policy validity
2 years, second year refundable if visa cancelled
What’s Not Covered
Pregnancy, childbirth, and dental care are excluded from this specific scheme.
A Genuinely Valuable Benefit Most Guides Miss
Pre-existing and chronic conditions are covered with no waiting period, unlike most standard policies, which typically exclude the first six months. There’s no truly free health insurance option for small businesses in the UAE, but at AED 320 a year, this scheme comes about as close as the market gets.
Small Business Health Insurance Plans by Provider
Daman Value Choice (Micro-SME, 1 to 10 Employees)
Tier
Annual Limit
Network
Pre-existing Conditions
Bronze
AED 500,000
1,000+ to 2,200+ providers
Up to AED 160,000-250,000
Silver
AED 750,000
2,700+ providers
Up to AED 500,000
Gold
AED 2,500,000
3,100+ providers
Up to AED 1,000,000
Separate pricing structures apply for Abu Dhabi versus Dubai and Northern Emirates registration. Daman publishes full tier details directly on its own product page.
MetLife and Other Insurers
MetLife and several other DHA-approved insurers offer their own Essential Benefits Plan-style SME packages, with broadly comparable structures. Worth comparing directly for price and network before committing, since this is one of the areas where small business health plans genuinely differ provider to provider.
Best Health Insurance Providers for Small Businesses in the UAE
Provider
Best For
Employees
Notes
Daman
Abu Dhabi Micro-SMEs
1-10
Tiered Value Choice plans, Gold/Silver/Bronze
MetLife
Dubai SME packages
SMEs
Essential Benefits Plan-style structure
ADNIC
Custom group plans
SME to large corporate
Fully customisable coverage
Sukoon
SME plans, Free Zone-compliant option
SMEs
Business 360 covers Free Zone requirements
Confirm current pricing and exact plan names directly with each provider, since product lineups are updated periodically.
Which Plan Is Right for Your Business?
1 to 10 employees: Daman Value Choice or a similar Micro-SME tiered plan
Registered in the Northern Emirates: the federal Basic Health Insurance Scheme, at AED 320/employee/year
Larger or growing workforce: a custom group plan from ADNIC, MetLife, or Sukoon
Free zone company: check your specific free zone’s approved insurer list, or a Free Zone-compliant product like Sukoon’s Business 360
How to Buy Health Insurance for Your Small Business
Confirm your mainland or free zone registration
Count your employees
Compare approved insurers
Choose a suitable plan
Submit employee documents
Pay the premium
Receive insurance certificates
Complete visa processing
Each step feeds into the next. Skipping ahead usually causes delays later.
Documents You’ll Usually Need
Trade licence
Emirates ID and passport copies
Visa copies
Employee list
Establishment card, if applicable
Exact requirements can vary slightly by insurer and emirate. Confirm the full list with your chosen provider before applying.
What Does It Cost to Insure a Small Team?
Costs vary by emirate, provider, and tier, but as a general guide:
Federal Basic Scheme (Northern Emirates): AED 320/employee/year
Micro-SME tiered plans (Daman Value Choice and similar products): higher, scaling with the annual limit and network breadth chosen
Confirm current pricing directly with your chosen insurer or broker, since rates and available tiers change.
What Affects the Premium?
Several factors move the price up or down, regardless of which provider you choose:
Employee age
Number of employees on the policy
Network size, wider access generally costs more
Annual coverage limit
Whether maternity is included
Whether dental is included
Chronic illness or pre-existing condition coverage
When Should You Buy Health Insurance?
Insurance generally needs to be in place at a specific point in the visa process, not before or after:
Business licence issued → Employee visa process starts → Insurance purchased → Policy activated → Emirates ID process completed
Arranging cover too late is one of the most common causes of delayed visa processing for small teams.
What About the Business Owner’s Own Health Insurance?
This is often overlooked. As a business owner, your own coverage depends on your visa category. If you’re on an investor or partner visa, you generally need to arrange your own qualifying policy, the same way you would for any employee, rather than assuming ownership alone provides cover. If you’re also on a Golden Visa, our guide on health insurance for Golden Visa holders in the UAE covers that specific route in more depth.
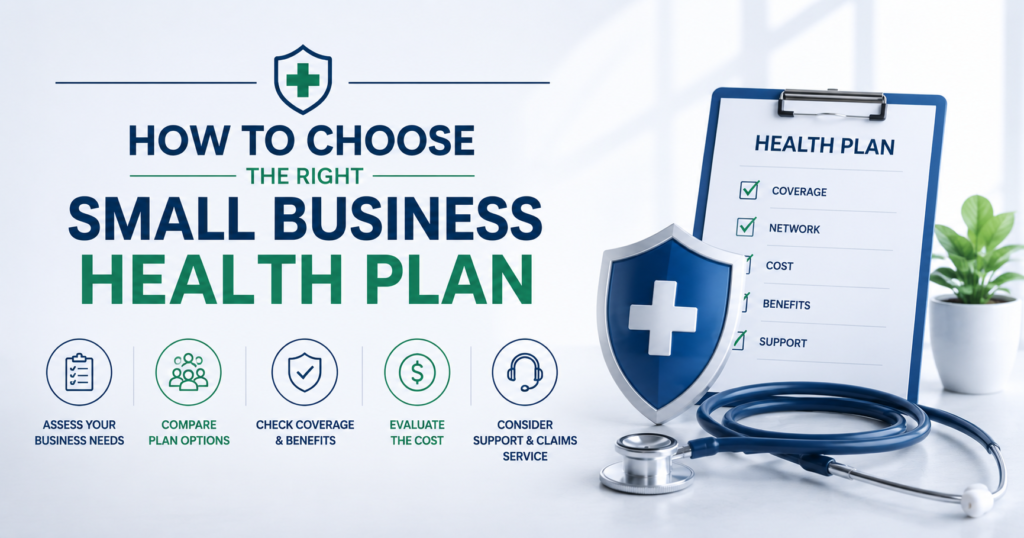
How to Choose the Right Small Business Health Plan
Confirm whether you’re mainland or free zone first, since this determines your compliance path
Count your total employees, since some products, like Daman’s Value Choice, are specifically capped at 1 to 10
Compare network size against where your team is actually likely to seek care
Check maternity, dental, and chronic condition coverage explicitly, since these vary significantly between the cheapest and mid-tier options
Confirm dependant coverage is included, extending insurance to spouses and children is a genuine retention factor, not just a compliance checkbox
Ask about claims processing speed and support responsiveness before signing, a plan that’s cheap but slow to pay out creates real friction for a small team
Get quotes from at least 2 to 3 DHA or DoH-approved providers before deciding
Free Zone Doesn’t Always Mean Zero MOHRE Contact
Even free zone businesses aren’t fully insulated from MOHRE. If you hire mainland employees or freelancers, work with mainland clients or suppliers, or move staff between a free zone and the mainland, you may still need to engage with MOHRE systems for those specific arrangements, even though your core company registration sits outside it. Once your policy is active, checking your health insurance status in the UAE confirms it’s live and correctly linked.
Common Mistakes to Avoid
Buying a plan before confirming mainland or free zone status
Choosing only on price, without checking the network
Ignoring the hospital network entirely
Forgetting to arrange the owner’s own coverage
Not checking the renewal date until it’s already overdue
Checklist Before You Purchase
Mainland or free zone confirmed
Employee count confirmed
2 to 3 insurers compared
Maternity and chronic condition coverage checked
Hospital network verified
Renewal date confirmed
If you’re still deciding, start with one question: is your company mainland or free zone? That single decision determines which authority you’ll deal with, which insurers you can choose from, and which plans are actually available to you.
Regulations and product availability change periodically, so always confirm the latest plan details with the relevant authority or insurer before purchasing.
Updates Section
Last verified: August 2026. Reflects MOHRE’s current published Basic Health Insurance Scheme terms, Daman’s current Value Choice product structure, and confirmed emirate-by-emirate regulatory splits.
Conclusion
Two things matter most when choosing a health insurance plan for small business owners in the UAE. First, whether your business is mainland or free zone fundamentally changes the compliance path and which providers you’ll deal with. Second, the federal Basic Health Insurance Scheme, at AED 320 a year, is a genuinely strong, often-overlooked option specifically for Northern Emirates businesses, with no waiting period for pre-existing conditions, a real advantage over most standard small business medical insurance.
Confirm current pricing and available tiers directly with a DHA or DoH-approved provider before choosing, since rates and product lineups shift over time.
Frequently Asked Questions
Q: Is health insurance mandatory for small businesses in the UAE?
A: Yes, across all seven emirates, though the specific rules and route depend on whether the business is mainland or free zone, and which emirate it’s registered in.
Q: What is an Essential Benefits Plan?
A: A simplified, DHA-compliant medical insurance package designed for small and medium businesses, also sometimes called an SME Pre-Packaged Solution.
Q: How much does small business health insurance cost in the UAE?
A: The federal Basic Health Insurance Scheme for the Northern Emirates costs AED 320 per employee per year. Micro-SME plans from providers like Daman cost more, scaling with the annual coverage limit and network size chosen.
Q: What are the cheapest health insurance plans for small business owners in the UAE?
A: The federal Basic Health Insurance Scheme, at AED 320 per employee per year, is generally the lowest cost compliant option, though it’s specific to the Northern Emirates and excludes pregnancy and dental cover.
Q: Is there a free health insurance plan for small business owners in the UAE?
A: No genuinely free option exists, health insurance is a paid, mandatory requirement for every employee. The Basic Health Insurance Scheme at AED 320/year is the closest thing to a low cost baseline.
Q: Do free zone businesses need to register with MOHRE for health insurance?
A: No. Free zone businesses aren’t required to register with MOHRE and typically arrange compliant insurance through their free zone’s own linked provider instead.
Q: Does the Basic Health Insurance Scheme cover pre-existing conditions?
A: Yes, without a waiting period, a genuinely uncommon benefit compared to most standard policies, which usually exclude the first six months.
Q: How many employees can a Micro-SME plan cover?
A: Daman’s Value Choice plan, for example, covers 1 to 10 employees plus their dependents.
Q: Does a small business owner need their own separate health insurance?
A: Yes, depending on the visa category. Investor or partner visa holders generally need to arrange their own qualifying policy rather than assuming business ownership alone provides coverage.
Q: Does a free zone company ever need to deal with MOHRE for health insurance?
A: Sometimes. While free zone businesses don’t need to register with MOHRE, hiring mainland staff, working with mainland clients, or moving employees between jurisdictions can still require MOHRE engagement for those specific situations.
Q: Can I change my insurer later?
A: Yes, typically at renewal. Switching providers mid-policy can involve breaking your current contract terms, so most businesses time a change to align with their renewal date.
Q: Can I insure only myself as a business owner, without staff?
A: Yes, if you’re a solopreneur or sole business owner, you still need a qualifying policy for your own visa, even without employees to insure.
Q: Can I include my family members in a small business health insurance plan?
A: Yes, most SME and Micro-SME plans allow dependents, spouses and children, to be added, though this typically comes at an additional cost per dependant.
Anees is a UAE-based content creator, writer, and SEO professional with over 12 years of experience. Since 2014, he has published research-backed guides on UAE visas, labour laws, jobs, traffic fines, and government services, all verified against official sources. He is certified in SEO by HubSpot Academy and Digital Marketing by Google Digital Garage.
12+ Years ExperienceHubSpot Academy — SEOGoogle Digital Garage
Disclaimer: This information is for general guidance only, based on publicly available UAE laws and regulations. It does not constitute legal advice. Always verify with official UAE government sources or a qualified legal professional.
Your email will not be published. Comments are reviewed before appearing.