UAE Visa Overstay Fine 2026: AED 50/Day RulesMinimum Salary to Sponsor Your Family Visa in UAEUAE Labour Law: Notice Period ExplainedHow to Check Your UAE Visa Status OnlineUAE Golden Visa Eligibility Requirements UpdatedUAE Visa Overstay Fine 2026: AED 50/Day RulesMinimum Salary to Sponsor Your Family Visa in UAEUAE Labour Law: Notice Period ExplainedHow to Check Your UAE Visa Status OnlineUAE Golden Visa Eligibility Requirements Updated
UAE Business Bank Account Requirements 2026: Documents, Eligibility, Fees and How to Apply
The UAE Times
–
–
– min read
Last updated: – · Based on official UAE sources
UAE business bank account requirements centre on five things: a registered legal entity, a valid trade licence, disclosed ownership, complete KYC documentation, and a clearly explained business activity. This sits alongside the other UAE laws topics business owners deal with regularly.
UAE business bank account applications can be delayed or declined when documentation is incomplete, the business activity is unclear, ownership cannot be adequately verified, or the bank needs more information about the source and expected movement of funds.
UAE Business Bank Account Requirements at a Glance
Requirement
Usually Needed?
Trade licence
Yes
Certificate of incorporation
Depending on entity type
MOA/AOA
Often
Passport copies
Yes
Emirates ID
If applicable
UAE residence visa
Bank/entity dependent
UBO information
Yes
Board resolution
If applicable
Proof of business address
Often
Business profile or plan
Often
Source of funds declaration
Depending on profile
Bank statements
Depending on business stage
Client or supplier contracts
If requested
VAT certificate
If applicable
There is no single UAE-wide checklist used by every bank. Banks can request additional documents depending on your company structure, ownership, business activity, residency, expected transactions, and risk profile.
What Are the UAE Business Bank Account Requirements?
A registered legal entity, mainland, free zone, or offshore, a valid trade licence or certificate of incorporation, full UBO disclosure, completed KYC and AML checks, a clearly defined business activity, and an authorised signatory.
Structure-Based Differences
Mainland companies: banks may request proof of office address and business operations, depending on the company and account type
Free zone companies: may use flexi-desk arrangements, but banks can request additional evidence that the business is genuine and operational
Offshore companies: require notarised documents and enhanced due diligence
Non-residents: additional overseas documentation and certification required
Documents Required to Open a UAE Business Bank Account
Company Documents
Trade licence or Certificate of Incorporation
Memorandum and Articles of Association (MOA/AOA)
Share certificates and board resolution
Office lease agreement or Ejari
Shareholder and Signatory Documents
Passport copies of all shareholders and directors
Emirates ID and UAE visa, if applicable
Proof of residential address, UAE and home country
UBO declaration
Business Documentation
Business plan or company profile
Source of funds declaration
Proof of business activity, contracts or invoices
Bank reference letter, where available
Additional Documents, Case-Specific
VAT registration certificate, if applicable
Contracts with existing clients or suppliers
CV or professional profile of each shareholder
Company website or profile, where available
Do Foreign Business Documents Need Attestation for a UAE Bank Account?
Often, yes. Foreign-issued corporate documents may need to be legalised or attested before a UAE bank accepts them.
The exact process depends on the document, the country of issue, and the specific bank’s requirements
The UAE is not a party to the 1961 Hague Apostille Convention, so a single Apostille stamp accepted in many other countries generally isn’t sufficient on its own here
Foreign documents commonly need certification through the relevant UAE consulate or embassy in the country of issue, followed by further legalisation through the UAE Ministry of Foreign Affairs
The exact route can vary by document type and bank
This process can take several weeks and carries fees per document
This is one reason many foreign businesses find incorporating directly in a UAE free zone simpler, our guide on UAE business visa requirements covers that route in more depth. Confirm the exact requirement for your specific documents directly with your chosen bank before assuming a fixed process.
How Business Activity Affects Your Application
Business/Activity Factor
What It Can Mean for Onboarding
Straightforward professional services
May involve relatively simpler documentation
International trade or import/export
Bank may ask about countries, suppliers, and customers involved
Cash-intensive activity
May require more information about expected cash flows
Complex ownership structure
More UBO and ownership documentation may be needed
Regulated or higher-risk activities
Enhanced due diligence may apply
Banks assess the overall customer and business risk profile rather than assigning every business activity a fixed, universal risk category.
Can You Open a UAE Business Bank Account Online?
Yes, increasingly. Digital-first options have narrowed the gap with traditional branch-based banking.
Mashreq NEO BIZ: launched a One-Day Service Promise in May 2026, the first UAE bank to guarantee business account opening within one day for eligible customers, backed by an AED 1,000 cashback guarantee if the commitment isn’t met, using AI-driven KYC and automated verification
Wio Bank: fully app-based onboarding, generally the fastest traditional-alternative option
Emirates NBD, ADCB, HSBC: still generally require an in-person meeting for most business account types, though document upload can often be done digitally in advance
UAE Business Bank Comparison
Every bank listed below offers multiple business account packages, so treat these as a starting point, not a fixed quote. Minimum balance and processing time depend on the specific account, your business profile, and current pricing, always confirm directly with the bank.
Bank
Business Account Options
Digital Application
Minimum Balance
Best Suited For
Emirates NBD
Multiple packages by business size
Partial
Varies by account/product
Mainland, established businesses
Mashreq (NEO BIZ)
Pro and Pro Plus, plus traditional tiers
Yes, One-Day Service Promise for eligible customers
Varies by account/product
Free zone companies, SMEs, digital-first businesses
Al Islami, Business Plus, Business Premium, e-Trader
Partial
Varies by tier
Sharia-compliant banking
Do UAE Business Bank Accounts Require a Minimum Balance?
Usually, yes, though the exact amount depends entirely on the bank and specific account package. Some digital-first accounts, including certain Wio and Mashreq NEO BIZ tiers, offer no minimum balance requirement, while traditional bank tiers can require anywhere from a modest sum up to AED 500,000 depending on the package. Falling below the required balance typically triggers a monthly fee rather than automatic account closure, confirm the exact terms with your chosen bank.
How to Open a UAE Business Bank Account, Step by Step
Choose your bank strategically, based on your nationality, activity, and structure
Prepare all documentation in advance
Submit the application, in person or through digital onboarding where available
Complete KYC and compliance review
Receive account approval and activation
How Long Does It Take to Open a UAE Business Bank Account?
Timelines are bank and product dependent, but the process generally follows this pattern:
Stage
Typical Range
Document preparation
1-2 weeks
Application submission
1 day
Compliance review
Bank/product dependent
Account activation
1-3 business days after approval
Some digital-first accounts can activate within a day for eligible customers, while accounts with more complex ownership or documentation needs can take several weeks. Confirm current timelines directly with your chosen bank.
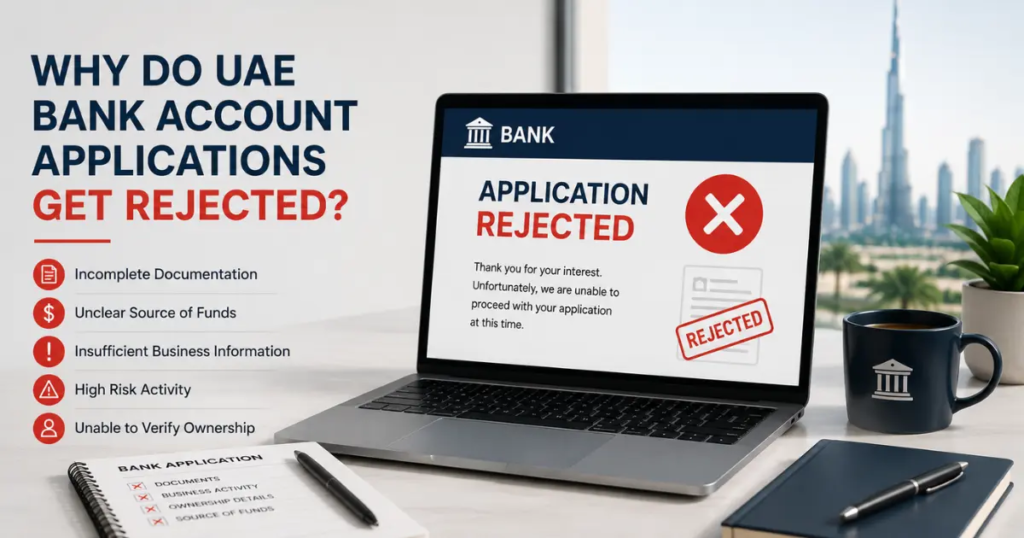
Why Do UAE Bank Account Applications Get Rejected?
Applications are delayed or declined for a range of reasons, most of them avoidable with proper preparation.
Incomplete documentation
Wrong bank for your specific business profile
Unclear source of funds
Mismatched information between trade licence activity and what’s described to the bank
Risk factors associated with the customer, business activity, ownership structure, or geographic exposure, which can trigger enhanced due diligence
A weak or unclear business plan
The silent rejection, where the bank simply stops progressing the application rather than issuing a formal decline
How Fast Can It Actually Go?
Speed depends heavily on documentation completeness and business complexity:
Complete documentation and a straightforward, low-risk profile can move fastest, sometimes within days on eligible digital accounts
Standard applications with a normal document set generally take longer
Layered ownership structures or higher-risk activities typically take the longest, since additional verification is required
What to Do If Your Application Is Rejected
Most guides stop at listing rejection reasons. Here’s the actual next step:
Ask the bank directly whether additional documents would change the outcome, some rejections are really just incomplete applications
Identify the likely specific issue rather than assuming it was arbitrary
Strengthen your source of funds evidence and business activity explanation before reapplying
Don’t resubmit identical paperwork to another bank without addressing the underlying issue
Choose a different bank that’s a better fit for your specific profile, since some banks simply don’t work with certain activities or nationalities
What Is a UBO and Why Does the Bank Need It?
A UBO, Ultimate Beneficial Owner, is the real natural person who ultimately owns or controls a company, even through layers of intermediate entities. Banks must trace ownership back to an actual individual, not just a holding company name, as part of UAE beneficial ownership regulations.
If your company is owned directly by individuals, this step is straightforward
If owned by another company, expect the bank to request an ownership chart and documents for each intermediate entity
The review takes longer the more layers exist between the account and the real owner
Source of Funds vs Source of Wealth: What’s the Difference?
Banks ask about both, and they mean different things.
Source of funds: where the specific money going into this account comes from, business revenue, an investment, a loan, savings
Source of wealth: the broader origin of a shareholder’s overall financial standing, prior business sales, inheritance, employment history, accumulated savings
Acceptable supporting documents include bank statements, sale agreements, employment records, or investment agreements, matched to whichever question is being asked.
What Do UAE Banks Check Before Approving a Business Account?
This is scattered across most guides, but it deserves one clear picture. Banks generally look at:
Business activity: what the company actually does, and whether it’s clearly explained
Ownership and UBO structure: who really owns and controls the company
Source of funds and source of wealth: where the money comes from and how the shareholders built their broader financial standing
Expected transaction volume: how much money is likely to move through the account, and how often
Countries you’ll send and receive money from: geographic exposure matters to compliance teams
Customers and suppliers: who the business actually deals with
Company age and financial history: newer companies get more scrutiny on the points above
Business address and operational presence: whether there’s genuine substance behind the licence
Consistency between documents and application: mismatches between what’s on paper and what’s described verbally are a common flag
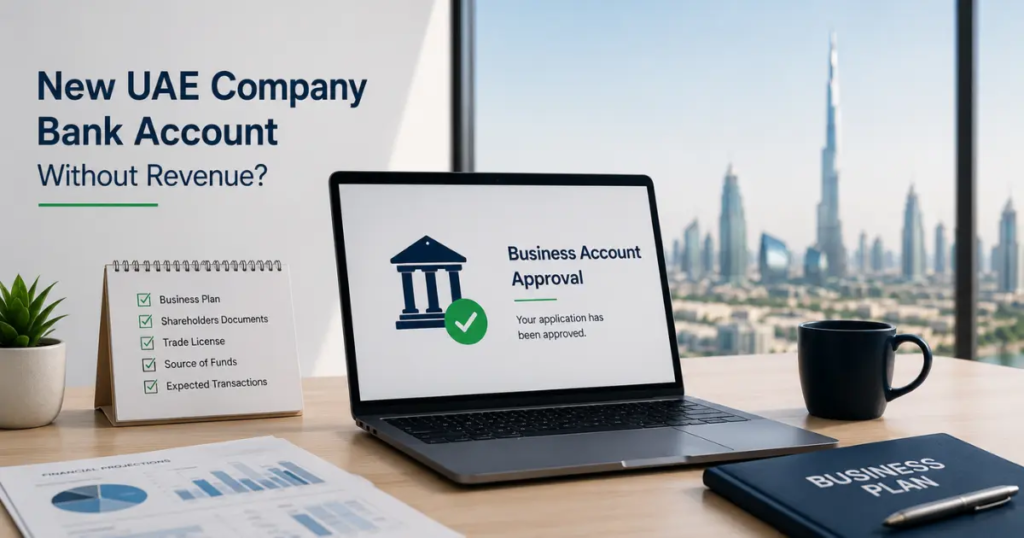
Can a New UAE Company Open a Bank Account Without Revenue?
Yes, this is common and doesn’t disqualify an application. Since a brand-new company has no transaction history, banks rely on other evidence instead:
A clear, detailed business plan explaining what the company will do and how it will earn revenue
Letters of intent or draft contracts with prospective clients, if available
Personal bank statements or a source of wealth explanation from the shareholders
A realistic explanation of expected monthly transaction volume
What If I Don’t Have Previous Business Bank Statements?
This is normal for a newly formed company, and it’s not a dead end. In place of business statements, banks typically accept personal bank statements from the shareholders, a clear source of wealth explanation, and a well-prepared business plan showing how the company expects to generate its first revenue.
Business Bank Account for Complex Ownership Structures
Companies with layered ownership, where the ultimate beneficial owner is itself a company rather than an individual, need additional documentation: an organisational chart showing the full ownership chain, documents for intermediate holding companies, and UBO identification tracing back to natural persons. Emirates NBD specifically distinguishes single-layer from multi-layer entities as separate application routes.
Personal vs Corporate Bank Account in the UAE
A personal bank account and a corporate account serve different purposes. Regular business transactions should be handled through an account appropriate for the business activity and the bank’s account terms. Using a personal account for commercial activity may conflict with the bank’s terms, so businesses should confirm the appropriate account type with their bank.
Once your corporate account is active, your business also needs to stay current on other compliance items, our guide on UAE Corporate Tax registration requirements covers the tax registration step most companies handle around the same time.
Conclusion
Two things matter most about UAE business bank account requirements. First, the process comes down to a genuine, well-documented business, disclosed ownership, and complete KYC paperwork, not an arbitrarily difficult process.
Second, foreign companies specifically need to budget extra time for document certification, since the UAE’s non-participation in the Hague Apostille Convention adds a real, multi-week step most guides don’t explain clearly.
Choose your bank based on your specific profile rather than the first branch you find, and prepare every document before you apply.
Frequently Asked Questions
What are the basic requirements to open a business bank account in the UAE?
A registered legal entity, valid trade licence or certificate of incorporation, full UBO disclosure, KYC/AML compliance, a clearly defined business activity, and an authorised signatory are generally required.
Can foreigners open a business bank account in the UAE?
Yes. Foreigners can open UAE business accounts, although non-residents may face additional document certification requirements depending on the bank and their circumstances.
Why do foreign company documents need extra certification for UAE bank accounts?
Foreign-issued company documents may need legalisation or certification before a UAE bank accepts them. The exact process depends on the document, country of issue, and the bank’s requirements.
How long does it take to open a UAE business bank account?
Timelines are bank- and product-dependent. Straightforward applications with complete documentation can move quickly, while complex ownership structures or applications requiring additional compliance checks typically take longer.
Why do UAE bank account applications get rejected?
Common reasons include incomplete documentation, unclear source of funds, inconsistent information, an unclear business activity, or a mismatch between the company’s licensed activity and what is described to the bank.
How much minimum balance do I need for a UAE business bank account?
It varies significantly by bank and account package. Some digital business accounts may have no minimum balance, while traditional business banking packages can require substantially higher balances. The required balance is typically an ongoing requirement rather than a one-time opening deposit.
Do I need to be Muslim to open an Islamic business account in the UAE?
No. There is no religious requirement to open an Islamic business account in the UAE. Non-Muslim business owners can also choose Islamic banking products.
Can I use my personal bank account for business in the UAE?
A personal account and a corporate account serve different purposes. Regular business transactions should be handled through an account appropriate for the business activity and the bank’s terms. Using a personal account for commercial activity may conflict with those terms, so confirm the appropriate account type with your bank.
Do I need to be a UAE resident to open a business bank account?
Not always. Some banks and digital alternatives accommodate non-residents, although certain traditional business accounts may prefer or require at least one authorised signatory to hold UAE residency.
Can a new UAE company open a bank account without any revenue?
Yes. New companies can apply even without previous revenue. Banks may instead assess the business plan, expected transaction activity, shareholder financial information, and source of funds or wealth.
What’s the difference between source of funds and source of wealth?
Source of funds refers to where the specific money entering the account comes from, such as business revenue or an investment. Source of wealth refers to the broader origin of a shareholder’s overall financial position, such as accumulated savings, previous business income, or proceeds from a business sale.
What is a UBO in UAE business banking?
UBO stands for Ultimate Beneficial Owner. It refers to the individual who ultimately owns or controls a company, including through layers of holding companies. Banks may need to trace the ownership structure back to the individuals who ultimately control the business.
What should I do if my UAE business bank account application is rejected?
Ask the bank whether additional documents or information could address the issue. Identify and fix the specific problem rather than simply submitting the same application elsewhere, and consider a bank or account product that better fits your business profile.
Can I open a UAE business bank account fully online?
Increasingly, yes. Some digital business banking products offer app-based or online onboarding, while traditional banks may still require an in-person meeting or additional verification depending on the account and applicant.
Can a free zone company open a UAE business bank account?
Yes. Free zone companies can apply for UAE business bank accounts. However, some banks may request additional evidence of business activity, ownership, address, or operations beyond the free zone trade licence.
Do I need a UAE residence visa to open a business bank account?
It depends on the bank, account type, and applicant profile. Some banks prefer at least one authorised signatory to hold UAE residency, while certain digital accounts and specific products may accommodate non-residents.
Updates Section
Last verified: August 2026. Reflects current bank-published minimum balances and timelines, Mashreq’s May 2026 One-Day Service Promise launch, and the current Hague Apostille Convention status for the UAE.
Anees is a UAE-based content creator, writer, and SEO professional with over 12 years of experience. Since 2014, he has published research-backed guides on UAE visas, labour laws, jobs, traffic fines, and government services, all verified against official sources. He is certified in SEO by HubSpot Academy and Digital Marketing by Google Digital Garage.
12+ Years ExperienceHubSpot Academy — SEOGoogle Digital Garage
Disclaimer: This information is for general guidance only, based on publicly available UAE laws and regulations. It does not constitute legal advice. Always verify with official UAE government sources or a qualified legal professional.
Your email will not be published. Comments are reviewed before appearing.