Health insurance for parents visa UAE requirements almost never get covered by your employer. If you are sponsoring a parent on a visa, arranging their medical insurance is your own responsibility, and the cost rises sharply with age. This guide covers real prices, the exact rules in Dubai and Abu Dhabi, and the mistakes that catch most sponsors off guard.
One distinction solves most of the confusion behind this search. A parent joining you on a residence visa needs an entirely different insurance product than a parent simply visiting on a visit visa. This guide walks through both, plus everything in between.
Do I Need Separate Health Insurance for My Parents’ Visa in the UAE?
Yes, in nearly every case. Health insurance for parents visa UAE sponsorship almost never comes bundled with an employer’s group health policy.
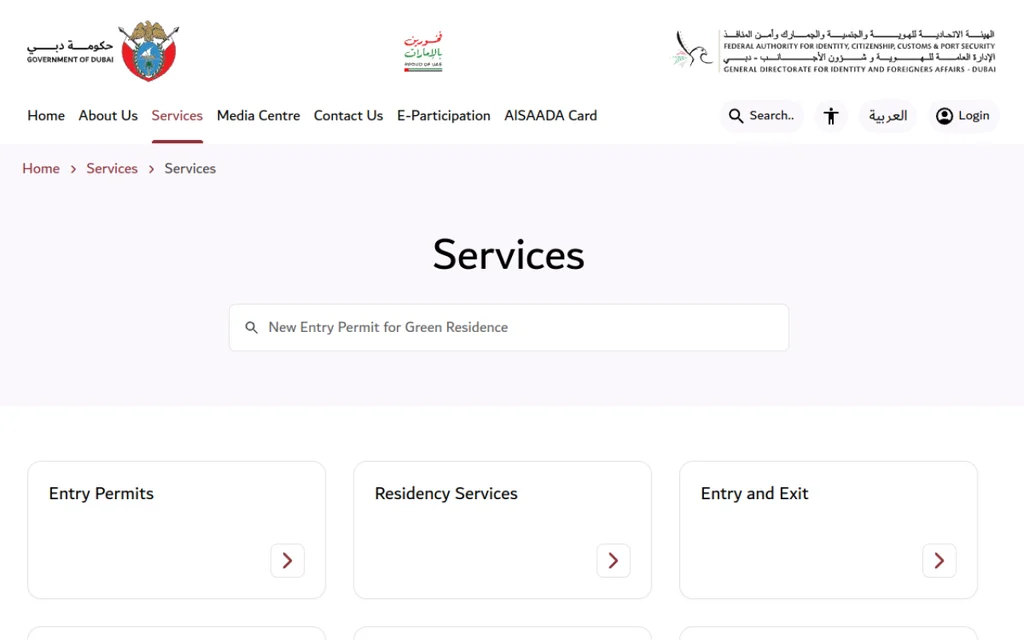
Screenshot: GDRFA Dubai services page on the official gdrfad.gov.ae website (captured October 2026).
This catches a lot of people off guard. Many assume that if their own insurance comes through work, their parent’s coverage works the same way. It does not. Employers insure the employee, and in some cases a spouse and young children. A parent falls outside that circle entirely, and becomes the sponsor’s own responsibility to insure.
Health Insurance for a Parent on a Residence Visa vs a Visit Visa
This distinction decides what kind of policy you need to buy.
Sponsoring a Parent on a Residence Visa
If your parents are living with you long term under your sponsorship, their coverage needs to be ongoing. It renews every year, alongside their visa, and both the visa issuance and its renewal depend on that policy staying active, a requirement confirmed directly on the UAE Government Portal. Our residence visa renewal guide covers the rest of that process.
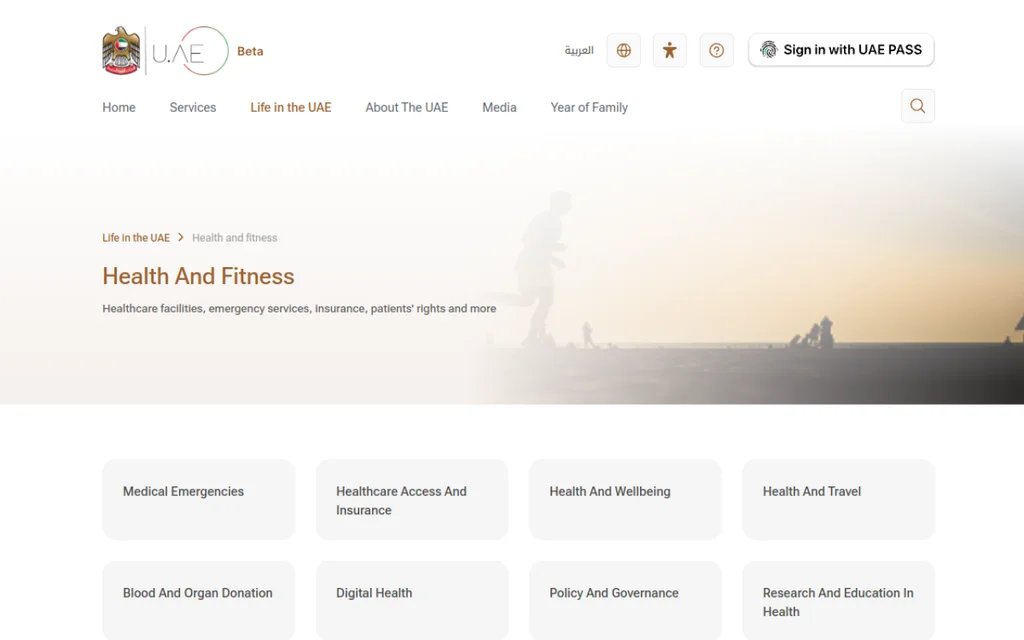
Screenshot: Health and Fitness section on the official u.ae website (captured October 2026).
Parents Visiting on a Visit Visa
If your parents are only visiting for a few weeks or months on a family visit visa, a full annual policy is the wrong product. Visitor medical insurance is built for this instead, a shorter term plan, usually capped around AED 150,000 in coverage, that runs for the length of the visit rather than a full year.
Knowing which of these two applies to your situation is the first real decision to make, before comparing a single premium.
How Much Does Health Insurance for Parents Cost in the UAE by Age?
Medical insurance for senior citizens in the UAE is priced almost entirely around age, health history, and the network you choose.
Age band
General cost pattern
60 to 65
Lower end of senior pricing, fewer restrictions
66 to 70
Noticeably higher premium, some plans require medical disclosure
71 to 75
Higher still, network choice and annual limit matter more
75 and above
Highest tier, medical disclosure typically required, fewer insurers willing to underwrite
The EBP Baseline for Parents
Dubai’s Essential Benefits Plan (EBP), the minimum legal tier, is priced by category for dependents. Typical market quotes are:
General non-working dependents aged 0 to 65: around AED 650 a year
Non-working spouses aged 18 to 45: around AED 1,600 a year
Elderly parents: around AED 2,500 a year, depending on the insurer
EBP eligibility for a dependent is based on the dependent’s own status as a non-working person, not the sponsor’s own salary. A parent who does not work generally qualifies for EBP regardless of how much the sponsor earns.
The Salary Rule Most Guides Miss
There is a separate, and much more important, salary rule specific to parents. To sponsor a parent’s residence visa in Dubai at all, the sponsor typically needs to earn:
Around AED 20,000 a month, which is the figure most commonly cited for Dubai
A different threshold may apply in some cases or emirates, so confirm your own case through Amer and GDRFA
This is far higher than the general AED 4,000 threshold used for sponsoring a spouse or children. Confirm the current figure with GDRFA or an Amer centre before assuming the lower family threshold applies to a parent.
Commercial Plans Beyond the EBP Tier
Seniors who need coverage beyond the EBP tier usually choose from three commercial plan levels. Premiums depend on the insurer, your parent’s age and health, and the network, so get quotes from at least two insurers or a licensed broker. For general premium levels by emirate, see our guide to health insurance costs in the UAE.
Commercial plan tier
Relative premium
Network scope
Typical co-payment
Standard
Lowest of the three
Public hospitals plus select private clinics
Higher co-payments per visit and for medication
Enhanced or Mid tier
Moderate
Broader private network, some larger hospitals
Lower co-payments, lower medication cost
Premium or Comprehensive
Highest
Full private network, leading hospitals
Lowest or no co-payment, often with dental and optical add ons
What Can Push the Cost Higher
A declared condition like diabetes, hypertension, cardiovascular disease, or arthritis can add a significant loading to the premium, depending on how the insurer underwrites it
Some mid tier plans use an exclusion rider instead, excluding the specific condition entirely rather than raising the premium
The Essential Benefits Plan carries an annual limit around AED 150,000, which can fall short for a major surgical procedure either way
A Quick Note on the “Basmah” Cancer Benefit
You may see this mentioned as a special new benefit for seniors in 2026. It is not new, and it is not age specific. Dubai’s Basmah initiative has existed since 2019, and it provides cancer and Hepatitis C screening and treatment for Essential Benefits Plan holders generally, most commonly Low Salary Band workers. If your parent’s policy sits on the EBP tier, this benefit may apply to them, just do not treat it as a senior only perk, since that is not what it actually is.
Dubai vs Abu Dhabi Rules for Parents’ Health Insurance
Here is how the two emirates compare.
Dubai, governed by Law No. 11 of 2013 and regulated by the Dubai Health Authority, requires the employer to insure the employee only. A parent is always the sponsor’s own responsibility, arranged separately. The minimum required annual coverage limit is AED 150,000.
Abu Dhabi, governed by Law No. 23 of 2005 and regulated by the Department of Health, only extends the employer’s obligation to a spouse and up to three children under 18. A parent is never included under an employer plan here either, and always falls to the sponsor. Abu Dhabi also sets a higher minimum annual coverage limit than Dubai, at AED 250,000, so a plan that meets Dubai’s minimum may not automatically meet Abu Dhabi’s.
What Does a Health Insurance Plan for Parents Need to Cover?
A compliant plan for a parent should include inpatient care, outpatient consultations, diagnostic tests, prescribed medication, and chronic condition management. Basic or EBP tier plans often carry a waiting period and lower annual limits, which matters more for an older parent who is statistically more likely to need care soon after the policy starts.
Many plans also cover select daycare treatments that do not require an overnight hospital stay, dialysis and chemotherapy sessions are common examples. Worth checking for specifically if your parent has an ongoing condition that needs regular treatment like this.
When Does a Basic Plan Make Sense, and When Should You Upgrade?
Not every parent needs the most expensive tier available. A basic or EBP level plan tends to work when your parent is in generally good health with no major pre-existing conditions, and access to public and approved clinics is acceptable for their needs.
An enhanced or comprehensive plan is often worth the extra cost if your parent has multiple chronic conditions or needs regular specialist care. It can also be a better choice if they take ongoing medications or need access to a wider network of private hospitals.
In many cases, a lower co-payment saves enough money over time to offset the higher premium. As a simple rule, if your expected out-of-pocket costs under a basic plan are higher than the upgrade cost, choosing the enhanced plan usually makes financial sense.
Pre Existing Conditions and the Waiting Period
This is one of the biggest cost variables in health insurance for parents above 60. Most UAE insurers apply a waiting period, typically 6 months but sometimes up to 12 depending on the plan tier, before a pre existing condition is actually covered on a new policy.
Keeping coverage continuous, with no gap between one policy ending and the next starting, generally avoids resetting that waiting period clock at renewal. Letting a policy lapse, even briefly, can mean starting the wait all over again.
There is a specific document that makes this work in practice: a Certificate of Continuity, issued by the previous insurer, confirming there was no gap in coverage. When switching providers, request this certificate and submit it to the new insurer, since it is generally what allows the new policy to waive the waiting period rather than treating the parent as a brand new applicant.
What Happens If a Condition Isn’t Disclosed Upfront?
This matters most when a claim is made.
Insurers assess every claim against the original health declaration you signed. If a known condition was left off that form, and it surfaces later at claim time, the insurer can deny the claim. In more serious cases, the entire policy can be voided.
Disclosing a condition upfront, even if it means accepting a waiting period or a higher premium, is a far safer position than facing a denied claim when your parent actually needs treatment.
Do Parents Need a Medical Test Before Getting Insured?
Often, yes. Insurers frequently ask for a medical disclosure form or a fitness assessment for applicants over a certain age, commonly around 65, especially for enhanced or comprehensive plans. This is an underwriting requirement set by the insurer, not a fixed visa rule, so it varies by provider and plan.
Documents and Information Insurers Typically Ask For
Having these ready in advance avoids delays:
Passport copy and the current visa page
Emirates ID, or the application acknowledgment if it is still processing
A completed health declaration form
Recent medical reports, generally within the last 6 months, including blood work or any specialist letters
A list of current medications
A brief medical history covering any surgeries or hospital stays in recent years
The sponsor’s own Emirates ID and visa copy
Get an Indicative Quote Before You Apply Formally
Ask a broker or insurer for a pre underwriting assessment before submitting a full application. This gives a realistic premium estimate and flags likely exclusions upfront, so there are no surprises at renewal, and no wasted formal applications.
Common Mistakes When Insuring a Sponsored Parent
Assuming an employer’s plan automatically covers a parent, it almost never does
Choosing a basic EBP tier plan for an older parent, then discovering the annual limit falls short
Letting coverage lapse between renewals, which can reset the pre existing condition waiting period. You can check your parent’s insurance status online before renewal
Confusing a short term visit visa product with a full residence visa policy
Conclusion
Getting health insurance for parents visa UAE sponsorship right starts with the type of visa: a parent living with you on a residence visa needs an annual policy tied to visa renewal, while a visiting parent needs a shorter visitor policy. Then budget realistically. The cheapest EBP tier meets the legal minimum, but most families sponsoring an older parent, especially one with a health condition, need more coverage than that baseline provides.
Before buying, compare plans by your parent’s age band, and confirm the pre existing condition waiting period terms in writing. That single check can prevent a denied claim exactly when your parent needs care the most.
Frequently Asked Questions
Do I need separate health insurance for my parents in the UAE?
Yes. Employer group plans almost never extend to a sponsored parent. As the sponsor, arranging and paying for their coverage is your own responsibility.
How much does health insurance for parents cost in the UAE?
It depends heavily on age and your own salary as the sponsor. Dubai’s basic EBP tier starts around AED 550 to 650 a year generally, but rises to roughly AED 2,500 a year once age loading applies to an elderly dependent. Enhanced and comprehensive plans, which many older parents need, cost considerably more, so compare quotes for your parent’s age and health.
Do my parents qualify for the cheaper EBP plan in Dubai?
Generally yes, since EBP eligibility for a dependent is based on that dependent being non-working, not on the sponsor’s own salary. A non-working parent typically qualifies for EBP pricing regardless of how much the sponsor earns.
What salary do I need to sponsor a parent’s visa in Dubai?
Parent sponsorship has its own, higher salary threshold, separate from the general family sponsorship rule. Dubai typically requires around AED 20,000 a month, and the exact requirement for your case is confirmed through Amer and GDRFA. This is well above the AED 4,000 threshold used for sponsoring a spouse or children.
Is medical insurance for parents in the UAE different for a visit versus living here?
Yes. A parent on a residence visa needs ongoing annual coverage tied to visa renewal. A parent visiting on a visit visa needs a shorter term visitor medical product instead.
Does my employer have to insure my parents in Abu Dhabi?
No. In Abu Dhabi, an employer’s obligation covers only a spouse and up to three children under 18. Parents are never included, and remain the sponsor’s own responsibility.
Is there a waiting period for pre-existing conditions on a parent’s health insurance?
Most insurers apply a waiting period, typically 6 to 12 months depending on the plan tier, for pre-existing conditions on a new policy. Keeping coverage continuous, without a gap, generally avoids resetting this period at renewal.
What happens if a parent’s pre-existing condition isn’t disclosed when buying insurance?
It creates real financial risk. Insurers assess claims against the original health declaration, so an undisclosed condition found later can lead to a denied claim, or in serious cases, the policy being voided entirely.
How much more does insurance cost for a parent with diabetes or another pre existing condition?
Expect a loading on top of the base premium, or an exclusion for that condition, depending on the insurer’s underwriting assessment.
Do parents need a medical test to get health insurance in the UAE?
Often yes, particularly for applicants over around 65 applying for enhanced or comprehensive plans. This is an insurer requirement, not a fixed visa rule, so it varies by provider.
What is the cheapest medical insurance for parents in the UAE?
Dubai’s Essential Benefits Plan is the legal minimum and the cheapest compliant option, at roughly AED 2,500 a year for an elderly parent. It meets the law, but its lower annual limit and basic network may not suit a parent with ongoing medical needs.
Is health insurance for parents above 60 more expensive than for younger dependents?
Yes, noticeably. Premiums increase with each age band from 60 onward, and applicants over 65 or 75 often face additional medical disclosure requirements that younger dependents do not.
What does health insurance for parents visa UAE sponsorship actually require?
It requires an active, compliant policy in the parent’s name, arranged and paid for by the sponsor, valid for as long as the residence visa itself stays active. It is checked at both visa issuance and every renewal.
What is a Certificate of Continuity, and do I need one for my parent’s insurance?
It is a document from the previous insurer confirming there was no gap in your parent’s coverage. Submitting it to a new insurer when switching providers is generally what allows the waiting period to be waived, rather than starting fresh as a new applicant.
Anees is a UAE-based content creator, writer, and SEO professional with over 12 years of experience. Since 2014, he has published research-backed guides on UAE visas, labour laws, jobs, traffic fines, and government services, all verified against official sources. He is certified in SEO by HubSpot Academy and Digital Marketing by Google Digital Garage.
12+ Years ExperienceHubSpot Academy — SEOGoogle Digital Garage
Disclaimer: This information is for general guidance only, based on publicly available UAE laws and regulations. It does not constitute legal advice. Always verify with official UAE government sources or a qualified legal professional.

Your email will not be published. Comments are reviewed before appearing.